Legal Intelligence · Bankruptcy & Restructuring

Bankruptcy & Restructuring legal & regulatory updates

Briefly tracks bankruptcy & restructuring developments — court rulings, legislation, gazette notices, and regulatory updates — from courts and regulators. 53 updates tracked in the past 30 days, last updated 14 Sept.

Get Bankruptcy & Restructuring updates in your inbox
Legal News
Kenya
Legal News

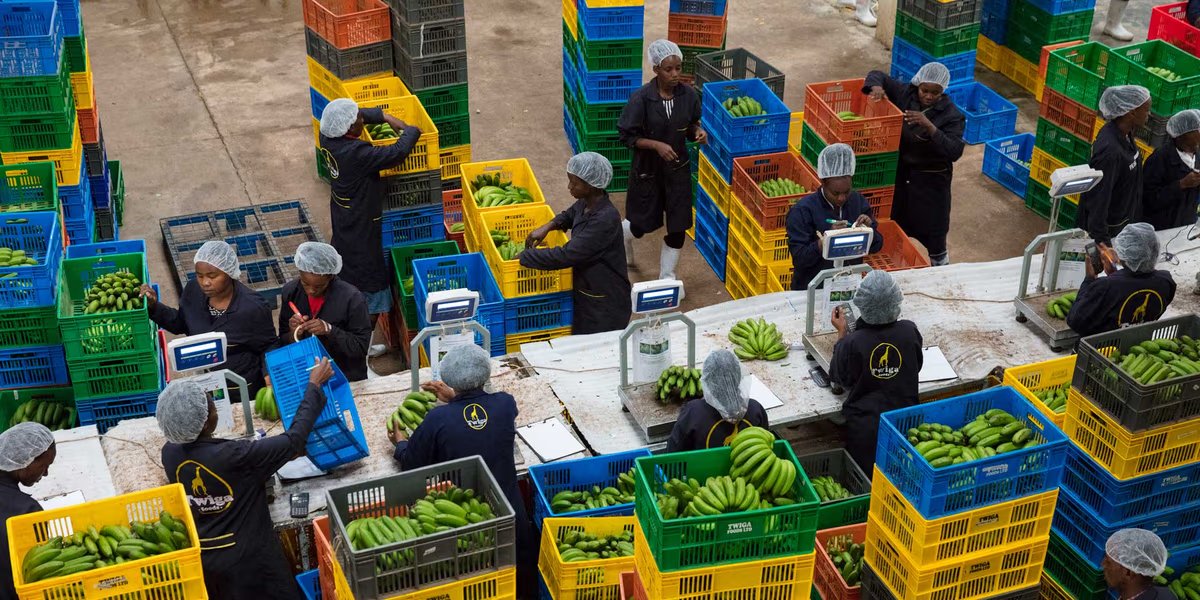
GT Flow Administration: Mohamed Mohamed Leads Kenya Debt Recovery

GT Flow Limited, formerly known as Twiga Foods One Limited, has been placed under administration in Kenya, with Mohamed Mohamed appointed as administrator, to facilitate the recovery of debts owed to its suppliers and other creditors. This significant development, announced via a Gazette Notice, effectively transfers control of the company's assets and management from its directors to the appointed administrator, marking a formal step in addressing the company's financial challenges. The powers of the company's directors to transact with assets are now suspended unless expressly permitted by the administrator, signaling a critical shift in corporate governance and operational control. This action comes amidst broader financial difficulties within the Twiga Foods ecosystem, including a separate High Court petition seeking the liquidation of Twiga Tatu SEZ Limited over outstanding debts. The outcome of the administration process for GT Flow Limited is not yet reported, but it is a clear indication of severe financial distress. This event carries substantial legal significance for practitioners, creditors, and businesses operating within Kenya's dynamic economic landscape. The appointment of an administrator under the Insolvency Act provides a structured legal framework for managing a financially distressed company, aiming either to rescue the company as a going concern or to achieve a better outcome for creditors than would be possible through liquidation. For creditors, this means a formal process for lodging claims and potentially recovering outstanding debts, albeit under the administrator's discretion and statutory priorities. For businesses, particularly those in the startup and tech sectors, it underscores the increasing financial pressures and tighter funding conditions, highlighting the importance of robust financial management and contingency planning. The cessation of directors' powers also has immediate implications for contractual relationships and ongoing business operations. The legal context for this administration is primarily Kenya's Insolvency Act, which governs corporate insolvency proceedings, including administration and liquidation. The High Court is the designated forum for such matters, overseeing petitions and appointments. Administration, as a statutory process, is distinct from liquidation, often serving as a pre-liquidation rescue mechanism. The Gazette Notice is a legally mandated publication to inform the public and creditors of such appointments, ensuring transparency and due process. The mention of a separate liquidation petition against Twiga Tatu SEZ Limited further illustrates the application of the Insolvency Act in addressing corporate financial distress. Key parties involved include GT Flow Limited, its administrator Mohamed Mohamed, its numerous suppliers and creditors, and the High Court. Practitioners should closely monitor the administrator's actions and communications, advising clients who are creditors on the process for submitting proofs of debt and understanding their rights and potential recovery prospects. Businesses with ongoing contracts or relationships with GT Flow Limited or other entities within the Twiga Foods ecosystem must immediately assess their exposure, review contractual terms, and understand the implications of the administrator's control over the company's assets and operations. Attorneys should also advise on the potential for restructuring plans under administration and the differences between administration and liquidation proceedings. This case serves as a crucial reminder for all businesses to conduct thorough due diligence on their trading partners and to be prepared for the legal ramifications of corporate insolvency.

14 Sept
Senegal
Legal News

Senegal Bondholders: Set Debt Restructuring Conditions

On Friday, an ad hoc group of Senegalese bondholders, recently formed, declared its demand for a fair, sustainable, and credible debt treatment based on sound economic assumptions and public policy commitments, as reported by Reuters on September 11, 2026. This development marks a critical juncture in Senegal's sovereign debt restructuring efforts, signaling the formal commencement of negotiations between the government and its private creditors. The bondholders' unified stance, emphasizing equitable burden-sharing and economically justifiable terms, sets the stage for potentially protracted and complex discussions. For practitioners in international finance, sovereign debt, and public law, this is a significant event as it will test the efficacy of the G20 Common Framework for Debt Treatments, particularly its "reinforced" version, which Senegal has opted to utilize. The outcome will not only impact Senegal's financial stability and future access to capital markets but also set precedents for other low-income countries seeking debt relief under similar frameworks. The legal context for these negotiations is multifaceted, drawing upon international financial law, principles of sovereign immunity, and the specific terms of the bond indentures. The G20 Common Framework, launched in 2020, provides a multilateral platform for coordinating debt treatments for eligible countries, aiming to ensure comparability of treatment among all creditors (official bilateral, multilateral, and private). The "reinforced" version, as indicated by Senegal, suggests a commitment to enhanced information sharing and parallel consultations, which are crucial for achieving a consensual and comprehensive restructuring. The involvement of a prominent legal counsel like White & Case, known for its expertise in sovereign debt restructurings, underscores the highly technical and legally intricate nature of these negotiations. Key parties involved include the ad hoc group of Senegalese bondholders, represented by their legal counsel White & Case, and the Government of Senegal. While the specific composition and amount of claims held by the bondholders are not detailed in the excerpt, their collective action signifies a coordinated approach to protecting their interests. The G20 Common Framework itself, though not a direct party to the negotiations, provides the overarching procedural and policy guidelines. The excerpt does not report any specific outcome of these negotiations, only the bondholders' initial conditions. Practising attorneys advising sovereign entities, international investors, or financial institutions should closely monitor the progress of these negotiations. Understanding the legal strategies employed by both the bondholders and the Senegalese government, particularly concerning the interpretation of "fairness," "sustainability," and "equitable burden-sharing" within the G20 Common Framework, will be paramount. The precedent set by Senegal's experience with the "reinforced" Common Framework will offer invaluable insights into the future of sovereign debt restructuring in Africa and beyond, requiring careful analysis of the legal and economic arguments presented by all stakeholders.
11 Sept
Senegal
Legal News

Senegal: Debt Reprofiling Bondholder Concerns Intensify, White & Case Engaged

Amundi, a European asset manager, expressed concerns on September 11, 2026, that the market price of Senegalese bonds does not fully reflect the risks associated with the country's upcoming debt "reprofiling" or restructuring. This assessment comes as Senegal moves forward with a plan to address an estimated $13 billion in previously undisclosed debt, two years after its revelation. The government's strategy, termed "reprofiling," involves extending maturities and renegotiating rates, a distinction from a full restructuring that authorities have been keen to emphasize. However, Sergei Strigo, Amundi's head of emerging debt, doubts the operation will be as benign as current bond prices suggest, especially with bonds trading around 50% of their nominal value. The core concern is that international bondholders may bear a disproportionate burden due to the exclusion of CFA franc-denominated debt and the preferential treatment typically afforded to multilateral and concessional creditors. Senegal's objective is to bring its debt, currently estimated at over 130% of GDP, onto a sustainable path to unlock a $2.2 billion program negotiated with the International Monetary Fund (IMF), whose debt sustainability analysis will ultimately dictate the extent of creditor contributions. The outcome of this matter is not yet reported. This situation carries significant financial and legal implications for international investors holding Senegalese sovereign debt. The semantic distinction between "reprofiling" and "restructuring" is critical, as it can influence market perception and the legal obligations of the debtor. Should international bondholders perceive an unfair distribution of the burden, it could lead to complex negotiations, potential legal challenges, and a re-evaluation of sovereign risk in emerging markets. The potential for differential treatment among creditor classes raises fundamental questions about equitable treatment and the enforceability of contractual rights in a sovereign debt context. For the broader market, it signals potential volatility and the need for heightened due diligence in assessing sovereign creditworthiness, particularly when hidden debts are revealed. The legal framework governing sovereign debt restructuring is multifaceted, primarily relying on the contractual terms of the bonds (often governed by foreign law, such as English or New York law) and principles of international financial law. While Senegal's domestic laws would apply to its internal debt, international bonds typically fall under the jurisdiction specified in their indentures. The involvement of the IMF introduces its policy frameworks for debt sustainability, which often include conditionality clauses that can influence domestic economic and legal reforms. The principle of *pari passu*, which generally implies equal treatment among creditors, is frequently a point of contention in such scenarios, though its practical application in sovereign restructurings can be complex and subject to interpretation. Key parties involved include the Government of Senegal as the debtor, Amundi representing a segment of international creditors, other international bondholders, and the International Monetary Fund. Attorneys advising international investors, particularly those with exposure to emerging market sovereign debt, should meticulously analyze the specifics of Senegal's debt reprofiling plan. This includes scrutinizing the proposed terms for extensions and renegotiations, and critically assessing the legal implications of excluding certain debt categories or providing preferential treatment to specific creditor groups. Understanding the governing law of the bonds and the enforceability of creditor rights in a sovereign context is paramount. Businesses with direct or indirect exposure to Senegalese markets should evaluate the broader economic stability implications of this debt situation. Legal teams should prepare for potential negotiations or disputes arising from the reprofiling process, focusing on the interpretation of contractual obligations and the potential for legal challenges if creditor interests are perceived to be unfairly prejudiced. Monitoring the IMF's debt sustainability analysis and its recommendations will be crucial for anticipating the final shape of the reprofiling efforts.

11 Sept
Senegal
Legal News

Senegal: AMJS & CN OHADA Launch OHADA Collective Procedures Senegal Seminar

The Association des Mandataires Judiciaires du Sénégal (AMJS) and the OHADA National Commission of Senegal commenced a three-day seminar in Saint-Louis on Friday to enhance the capacities of judicial actors regarding the implementation of the OHADA Uniform Act on Collective Insolvency Proceedings. This initiative is profoundly significant for the Senegalese legal and business landscape. By focusing on the "bonnes pratiques" (best practices) for the OHADA Uniform Act on Collective Insolvency Proceedings (Acte uniforme portant organisation des procédures collectives d’apurement du passif), the seminar aims to standardize and improve the application of insolvency law across the country. For practitioners, this means a potential for greater predictability and efficiency in handling corporate distress, debt restructuring, and liquidation cases. Enhanced judicial understanding can lead to quicker resolutions, better protection for creditors, and more viable pathways for businesses facing financial difficulties, ultimately fostering a more stable economic environment. The legal context for this development is rooted in the supranational OHADA legal framework, specifically the Uniform Act on Collective Insolvency Proceedings, which is directly applicable in Senegal. This Act provides a comprehensive legal regime for preventing and resolving corporate insolvency, including preventive conciliation, accelerated rehabilitation, and liquidation procedures. Senegal, as a member state of OHADA, is bound by these uniform laws, which aim to harmonize business law across West and Central Africa. The seminar targets judicial actors, implying judges, court registrars, and insolvency practitioners, who are central to the effective application of these complex legal provisions within the Senegalese court hierarchy, particularly commercial courts. Key parties involved include the Association des Mandataires Judiciaires du Sénégal (AMJS), which represents insolvency practitioners, and the OHADA National Commission of Senegal, responsible for promoting and overseeing the implementation of OHADA law domestically. The primary beneficiaries are the judicial actors themselves, whose capacities are being reinforced, and by extension, businesses, creditors, and debtors who rely on a well-functioning insolvency system. The outcome of this specific seminar is not reported, but its objective is clearly capacity building. Practising attorneys and legal professionals in Senegal should closely monitor the outcomes and recommendations stemming from such capacity-building initiatives. A deeper understanding of the OHADA Uniform Act on Collective Insolvency Proceedings, including its practical application and any emerging best practices, is crucial for advising clients effectively. This includes guiding businesses through preventive measures, representing creditors in recovery efforts, or assisting debtors in navigating restructuring or liquidation processes. Staying abreast of these developments will ensure compliance and strategic advantage in a continually evolving legal landscape.

11 Sept
India
Case Law

NCLAT: Resolution Plan Applicant Death Does Not Invalidate IBC

The National Company Law Appellate Tribunal (NCLAT) has definitively ruled that a resolution plan submitted under the Insolvency and Bankruptcy Code (IBC) does not automatically become invalid or fail simply because the resolution applicant who submitted it passes away before the plan receives final approval. In the case of *Arun Kumar Singh Vs Genius Exports*, the NCLAT, comprising Judicial Member Justice N Seshasayee and Technical Member Indevar Pandey, addressed what it termed a “blind spot” in the IBC, asserting that such a plan can still be thoroughly examined for its viability and potential for implementation, including through the involvement of the deceased resolution applicant’s heirs. This decision overturns a previous ruling by the National Company Law Tribunal (NCLT) which had rejected a CoC-approved plan for Genius Exports Private Limited following the death of its maker, Digvijay Nath Tripathi, and subsequently ordered the company's liquidation. This NCLAT ruling carries significant legal weight for the insolvency regime in India, providing much-needed clarity on an unforeseen contingency within the IBC framework. Its primary significance lies in preventing the premature liquidation of corporate debtors solely due to the demise of a resolution applicant, thereby upholding the core objective of the IBC to maximise asset value and promote resolution over liquidation. For practitioners, this decision safeguards the efforts invested by the Committee of Creditors (CoC) in approving a resolution plan and offers a pathway for continuity, potentially reducing the risk for prospective resolution applicants. The legal context is firmly rooted in the Insolvency and Bankruptcy Code, 2016, which governs corporate insolvency resolution processes, and the hierarchical structure of the NCLT and NCLAT, where the latter's pronouncements serve as binding precedents for the former. The NCLAT's distinction between a resolution applicant and statutory office holders like resolution professionals or liquidators is crucial, highlighting that the former's role is primarily that of a proposer rather than an indispensable executor. The key parties involved in this landmark decision include the corporate debtor, Genius Exports Private Limited, the deceased resolution applicant, Digvijay Nath Tripathi, and the Committee of Creditors (CoC) who had initially approved the plan. The National Company Law Tribunal (NCLT) made the initial decision to reject the plan, which was then challenged before the National Company Law Appellate Tribunal (NCLAT). For insolvency professionals, corporate lawyers, and businesses contemplating or undergoing insolvency proceedings, the practitioner takeaway is clear: the death of a resolution applicant does not spell the automatic end of a resolution plan. Attorneys should advise clients to explore mechanisms for plan continuity, such as involving heirs or alternative entities, and to ensure that resolution plans are robust enough to withstand such unforeseen events. This ruling reinforces the NCLAT's commitment to a pragmatic interpretation of the IBC, prioritising resolution and value maximisation, and practitioners must now factor this precedent into their strategic advice and drafting of resolution plans.

11 Sept

Bankruptcy & Restructuring coverage by jurisdiction

Other topics