
Allahabad HC: 18% GST on Legal Research Tools Upheld
Summary
- The Allahabad High Court dismissed a PIL challenging the 18% GST on online legal research tools.
- Advocate Aniket Gupta argued these services, classified under SAC 998431, are essential and not luxury items.
- The 18% GST rate has been in effect since 2017, established by Notification No. 11/2017-Central Tax (Rate).
- The court questioned the petitioner's unexplained delay in challenging a tax rate that had been in place for nearly a decade.
- The ruling confirms the continued applicability of the 18% GST rate for online legal research services in India.
What Happened
This ruling by the Allahabad High Court reinforces the existing tax liability for online legal research tools in India, confirming that the 18% GST rate under SAC 998431 remains applicable.
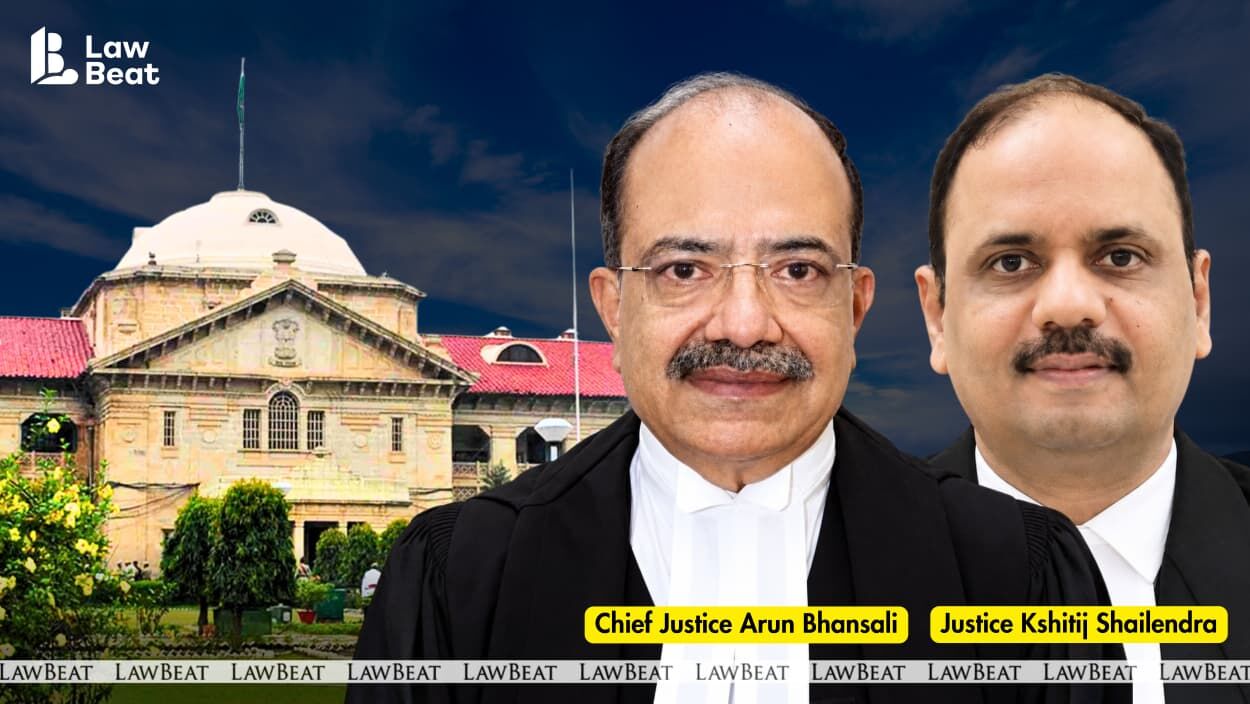
The Allahabad High Court recently rejected a public interest litigation (PIL) that sought to challenge the 18% Goods and Services Tax (GST) levied on online legal research tools. This significant decision, made on October 26, 2026, by a bench comprising Chief Justice Arun Bhansali and Justice Kshitij Shailendra, upholds the existing tax framework for these services.
Advocate Aniket Gupta, the petitioner in the case of Aniket Gupta vs. Union of India and 4 others, initiated the PIL. He argued that online legal research tools are indispensable for legal professionals, enabling them to verify judgments and thereby prevent instances of professional misconduct, such as citing overruled or fabricated rulings. Gupta contended that these services are not luxury items and, consequently, should not be subjected to an 18% GST rate, specifically requesting either a distinct classification or a concessional rate for these essential legal resources.
Legal and Regulatory Context
The 18% GST rate applied to online legal research tools has been consistently in effect since 2017. This tax structure is rooted in notifications issued that year, notably Notification No. 11/2017-Central Tax (Rate) dated June 28, 2017, along with its subsequent amendments and corresponding Integrated GST (IGST) and state-specific notifications.
These services are formally classified under Service Accounting Code (SAC) 998431. This code broadly encompasses online information and database access or retrieval services. Within this category, various online text-based information services, such as digital books, newspapers, periodicals, and directories, are also included. The 18% rate is specifically composed of 9% Central GST and 9% State GST for transactions occurring within a single state, while the IGST framework governs inter-state supplies.
The Court's Rationale
The Allahabad High Court's bench, led by Chief Justice Arun Bhansali and Justice Kshitij Shailendra, dismissed the petition primarily due to significant reservations regarding the timing of the challenge. The court observed that the 18% GST rate on online legal research tools had been consistently applied and publicly known since 2017, nearly a decade prior to the filing of the PIL.
Advocate Gupta, who was enrolled in 2020 and indicated six years of practice, failed to provide any satisfactory explanation for his "sudden awareness" of the tax rate's alleged unreasonableness in 2026. The judges explicitly stated that such an abrupt challenge to a long-standing tax treatment, without a compelling justification for the considerable delay, could not be countenanced. The court emphasized that the petition did not indicate any specific event or change in circumstances that might have prompted the advocate to question a rate that had been firmly in place for several years. This lack of explanation for the belated challenge was central to the court's decision to dismiss the plea.
Why It Matters
This ruling by the Allahabad High Court reinforces the existing tax liability for online legal research tools in India, confirming that the 18% GST rate under SAC 998431 remains applicable. For legal professionals and compliance officers across the country, this decision means the current tax structure for these essential services is definitively upheld, requiring continued adherence to the established rate.
Beyond the immediate tax implications, the court's decision sends a clear message regarding the timing of challenges to established tax rates. It strongly suggests that petitions questioning long-standing tax policies without a compelling and well-articulated explanation for the delay may face similar scrutiny and potential dismissal. The case, Aniket Gupta vs. Union of India, therefore underscores the judiciary's expectation for petitioners to justify the belated nature of their grievances, particularly concerning tax regimes that have been in force for several years.
Practical Implications
Lawyers and compliance officers should be aware that the 18% GST rate on online legal research tools, classified under SAC 998431, remains in effect as the Allahabad High Court dismissed a challenge to it. This ruling confirms the existing tax liability for these services, and future challenges to long-standing tax rates may face similar scrutiny regarding their timing.
Source
How does this affect you?
Get an AI analysis of this article grounded in your jurisdictions, practice areas, and any policy documents you've uploaded to Wansom.
Finish Reading the Full Story and the Expert Analysis.
Wansom is AI and can make mistakes.