
Rwanda: Public Servants Must Repay Lost Funds Under New Order
Summary
- Rwandan public servants must now repay lost government funds or property within 30 days under Ministerial Order No 010/26/10/TC.
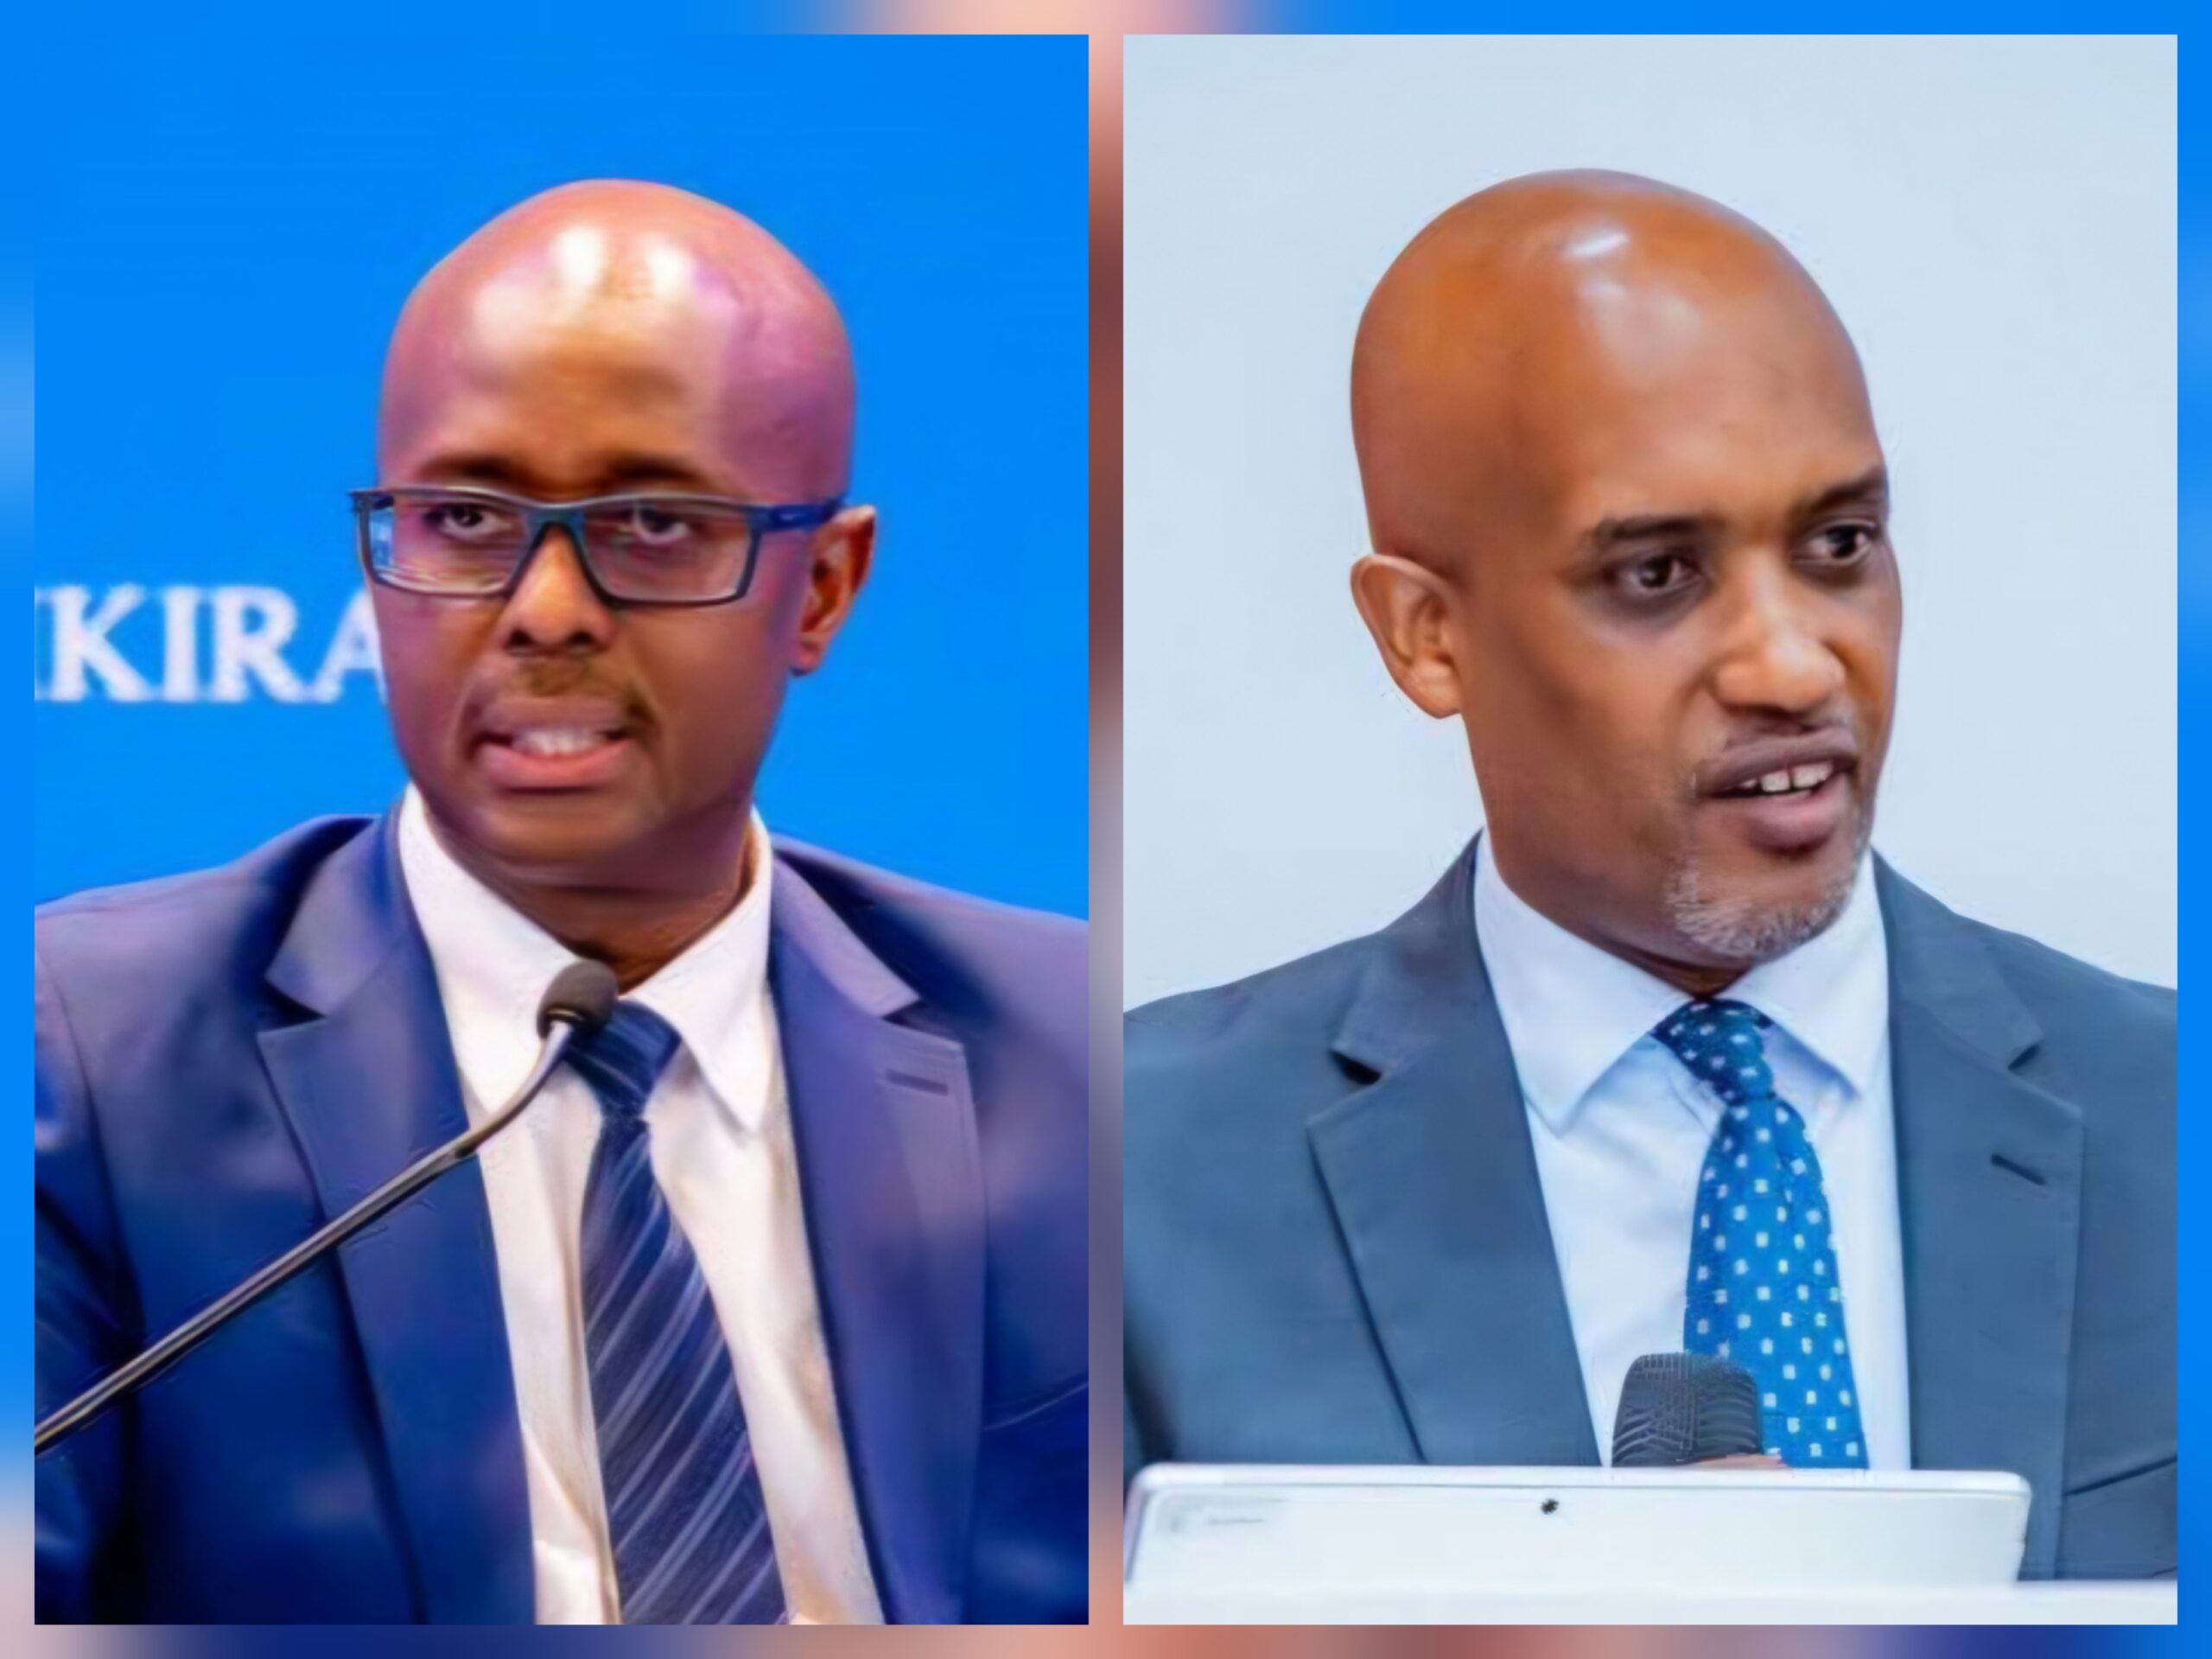
- Finance Minister Yusuf Murangwa and Justice Minister Dr Emmanuel Ugirashebuja issued the new rules, making employees financially responsible for losses due to their actions or omissions.
- The order mandates immediate reporting of suspected losses, thorough investigations, and legal action for non-payment, but allows for installment plans or write-offs in specific cases.
- New provisions include an "impromptu budget line" for unforeseen emergency spending at both central and local government levels.
- Public institutions are now required to separate financial responsibilities, establish internal audit functions, manage financial risks, and insure public assets against specified risks.
New Accountability Framework
Under the recently enacted Ministerial Order No 010/26/10/TC, published in the Official Gazette on October 30, employees found responsible for such losses are now required to repay the full amount within a 30-day period.
Rwanda has implemented stringent new regulations holding public servants personally accountable for any government funds or property lost due to their actions or omissions. Under the recently enacted Ministerial Order No 010/26/10/TC, published in the Official Gazette on October 30, employees found responsible for such losses are now required to repay the full amount within a 30-day period. This directive, championed by Finance Minister Yusuf Murangwa and Justice Minister Dr Emmanuel Ugirashebuja, marks a significant shift in Rwanda public finance management, extending financial responsibility directly to individual government employees.
Upon discovery of a loss, the head of the relevant institution must issue a written notice to the responsible employee, detailing the amount owed and demanding payment within the stipulated 30 days. While the primary expectation is prompt repayment, the regulations do permit payment to be made in reasonable installments if necessary. Failure to comply with these repayment demands can lead to legal proceedings initiated by the state before a competent judicial authority to recover the outstanding funds.
The scope of these new rules is broad, encompassing central government institutions, various local government entities, and non-commercial public institutions. Public servants are now mandated to immediately report any suspected loss of public money or property to their direct supervisors, as well as to the official responsible for asset management and the institution's chief budget manager. Every reported incident, regardless of how it comes to light, must be thoroughly investigated. If a loss suggests a criminal offense, the matter must be escalated to the appropriate investigative authorities. Employees who dispute their responsibility for a loss have the right to refer the matter to the courts for a final determination and potential recovery of funds. However, the regulations also provide for certain exceptions, allowing losses to be written off if they are the result of unavoidable circumstances or if, following a comprehensive investigation, the funds are deemed unrecoverable.
Enhanced Financial Controls and Asset Protection
Beyond individual accountability, the new Ministerial Order also introduces robust measures aimed at strengthening overall financial controls within public institutions. A key requirement is the strict separation of financial responsibilities, ensuring that no single employee or group of employees controls all stages of budgeting, payments, asset management, and accounting processes. This structural change is designed to create checks and balances, reducing opportunities for financial mismanagement.
Furthermore, every public institution is now obligated to establish and maintain an internal audit function, complemented by an independent audit committee. These bodies are tasked with overseeing financial operations and ensuring compliance. Institutions must also develop and implement comprehensive systems specifically designed to identify and manage financial risks proactively. A critical new provision mandates that all public assets must be adequately insured against specified risks. For instance, government buildings are required to have coverage against perils such as fire, earthquakes, and floods, while movable property must be protected against fire, theft, and floods, thereby safeguarding public resources against unforeseen events.
Emergency Budget Provisions
In addition to the new liability and control measures, the order establishes a novel framework for emergency government spending, referred to as an "impromptu budget line." This provision creates a dedicated reserve for urgent and unforeseen expenditures that were not initially included in the annual budget. At the central government level, the Ministry of Finance and Economic Planning will be responsible for managing this reserve. Ministries facing unexpected financial needs can submit requests for additional funding, provided they offer clear justification for the expenditure. The Finance Minister must then approve the allocation and ensure the funds are transferred to the relevant institution's budget before any spending can occur. Institutions receiving these emergency funds are subsequently required to submit quarterly reports detailing their utilization.
Local government entities will also benefit from their own emergency budget provisions, with their respective executive heads authorized to approve such spending. Similar to central government bodies, these local institutions must provide quarterly reports to their councils, ensuring transparency and oversight of emergency expenditures. The Ministerial Order does not specify a fixed amount or percentage of the national budget for these emergency allocations; instead, their size will be determined during the annual budget preparation process, allowing for flexibility based on prevailing economic conditions and anticipated needs.
Underlying Concerns and Impact
These comprehensive reforms are being introduced against a backdrop of persistent concerns regarding the effective management and recovery of public funds in Rwanda. Reports from the Auditor General have consistently highlighted challenges in this area. For example, the Auditor General's report for the financial year ending June 2025, which was presented to Parliament in May 2026, indicated that Rwf1.47 billion was recovered through preventive audits. This figure represents a notable decrease compared to the Rwf9.3 billion recovered in the previous year, underscoring the ongoing need for more robust financial oversight and accountability mechanisms. The new regulations, therefore, represent a concerted effort by the Rwandan government to address these systemic issues and ensure greater fiscal discipline and protection of public assets.
Practical Implications
Lawyers advising public institutions or public servants in Rwanda must understand the new Ministerial Order No 010/26/10/TC, which imposes personal financial liability on employees for lost government funds or property, requiring repayment within 30 days. Compliance officers should immediately review and update internal financial controls, audit functions, and asset insurance policies to mitigate risks under these new regulations.
Source
How does this affect you?
Get an AI analysis of this article grounded in your jurisdictions, practice areas, and any policy documents you've uploaded to Wansom.
Wansom is AI and can make mistakes.