
Kenya: Ruto Approves 90-Day Petroleum VAT 8% Extension
Summary
- President William Ruto has approved a 90-day extension of the 8 percent VAT on petroleum products, enabled by the Tax Laws (Amendment) Act, 2026.
- This extension follows EPRA's latest fuel price review, which saw significant increases in petrol, diesel, and kerosene prices for the October 15 to November 14 cycle.
- EPRA attributed the price adjustments to rising landed costs of imported refined petroleum, despite the government's policy to cushion consumers.
- The Motorists Association of Kenya (MAK) has demanded an independent audit of the fuel price review and the government-to-government petroleum import arrangement.
- MAK seeks greater transparency from EPRA, requesting detailed pricing worksheets and full disclosure of the G-to-G deal's financial specifics.
Extension of Reduced Petroleum VAT Rate
The `Tax Laws (Amendment) Act, 2026` grants the Treasury Cabinet Secretary the authority to implement such extensions, ensuring the continuity of the temporary reduced rate.
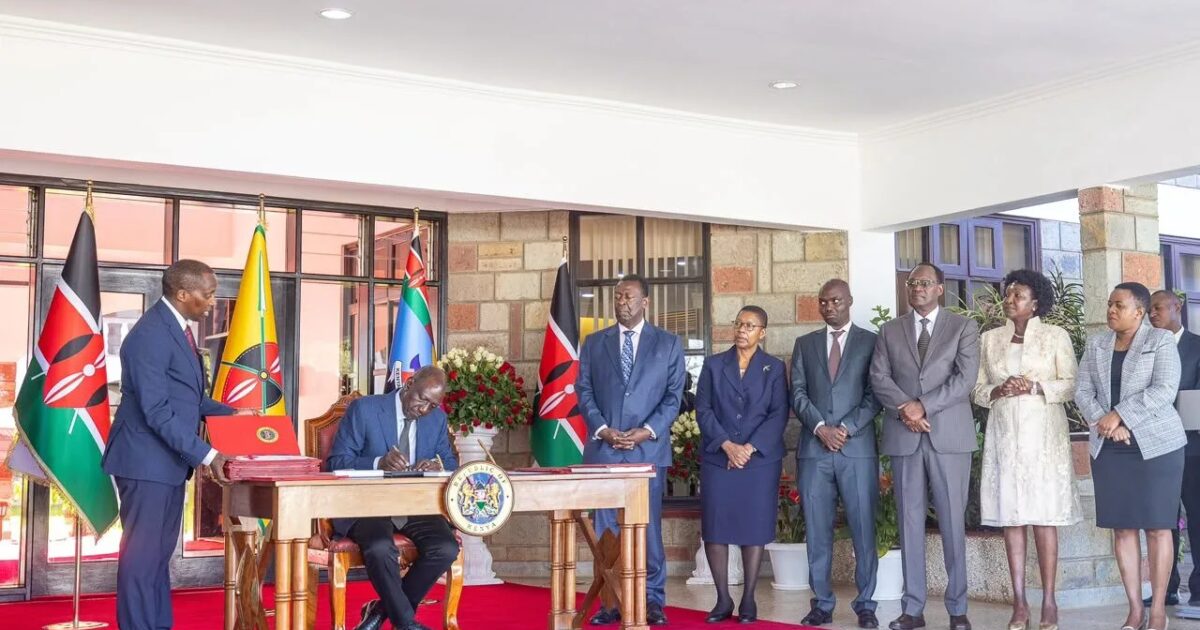
President William Ruto has formally approved a 90-day extension for the reduced 8 percent Value Added Tax (VAT) on petroleum products. This significant decision, signed into law at Eldoret State Lodge on a Friday, follows closely on the heels of the Energy and Petroleum Regulatory Authority's (EPRA) latest fuel price review, which already incorporated this same VAT rate. The `Tax Laws (Amendment) Act, 2026` grants the Treasury Cabinet Secretary the authority to implement such extensions, ensuring the continuity of the temporary reduced rate.
This `Ruto fuel VAT extension` comes as motorists in Kenya face increased pump prices. EPRA's announcement on October 14 set new maximum retail prices effective from October 15 to November 14. In Nairobi, petrol prices saw an increase of Sh12.93, reaching Sh226.96 per litre. Diesel also rose by Sh9.90, bringing its cost to Sh227.76 per litre. Kerosene experienced the most substantial adjustment, climbing by Sh28.49 to Sh219.87 per litre, despite the continued application of the 8 percent `Kenya petroleum products VAT rate`.
Regulatory Context and Price Drivers
EPRA confirmed that the recently announced prices for petroleum products included the 8 percent VAT, a measure consistent with the government's strategy to alleviate the impact of elevated international petroleum prices on consumers. The previous period of VAT relief had concluded on October 14, prompting discussions regarding the timing and legal basis for the current extension. The `EPRA fuel price review Kenya` attributed these latest price adjustments primarily to an increase in the weighted average cost of imported refined petroleum products.
Specifically, the regulator reported that the average landed cost of imported petrol surged by 11.81 percent, moving from US$874.26 per cubic metre in August to US$977.55 in September. Diesel's landed cost also increased by 11.32 percent, from US$957.05 to US$1,065.38 per cubic metre. Kerosene experienced a 9.41 percent rise in its landed cost, from US$1,003.87 to US$1,098.31, contributing to the overall upward trend in domestic fuel prices.
Public Concerns and Demands for Transparency
Despite the `Kenya petroleum VAT 8% extension`, the recent price hikes have intensified public concerns regarding the escalating costs of transport, household energy, and essential goods. In response, the Motorists Association of Kenya (MAK) has publicly called for an independent audit of both the latest `EPRA fuel price review Kenya` and the government's government-to-government (G-to-G) petroleum import arrangement.
MAK has specifically questioned the correlation between changes in landed costs and the final pump prices, highlighting kerosene as a particular point of contention. Kerosene recorded the largest percentage increase at the pump, yet it had the lowest reported percentage increase in its landed cost. To address these discrepancies, MAK has urged EPRA to release comprehensive pricing worksheets detailing international benchmarks, landed costs, exchange rates, freight charges, insurance, taxes, levies, margins, and any other applicable adjustments. Furthermore, the association has demanded full disclosure of the costs and benefits associated with the G-to-G arrangement, including supplier premiums, financing costs, freight charges, and foreign-exchange exposure, asserting that consumers deserve to differentiate between the effects of global market fluctuations and domestic policy decisions.
Practical Implications
Compliance officers and legal counsel for businesses in the energy, transport, and logistics sectors should note the continued application of the 8% VAT rate on petroleum products for an additional 90 days, as empowered by the Tax Laws (Amendment) Act, 2026. This impacts pricing, budgeting, and tax compliance, requiring adjustments to financial models and ensuring adherence to the temporary reduced rate.
Source
How does this affect you?
Get an AI analysis of this article grounded in your jurisdictions, practice areas, and any policy documents you've uploaded to Wansom.
Finish Reading the Full Story and the Expert Analysis.
Get the latest legal & regulatory intelligence in Kenya
Wansom is AI and can make mistakes.