Legislation
Ron Bimwala Proposition: 1% TVA for RDC Essential Goods
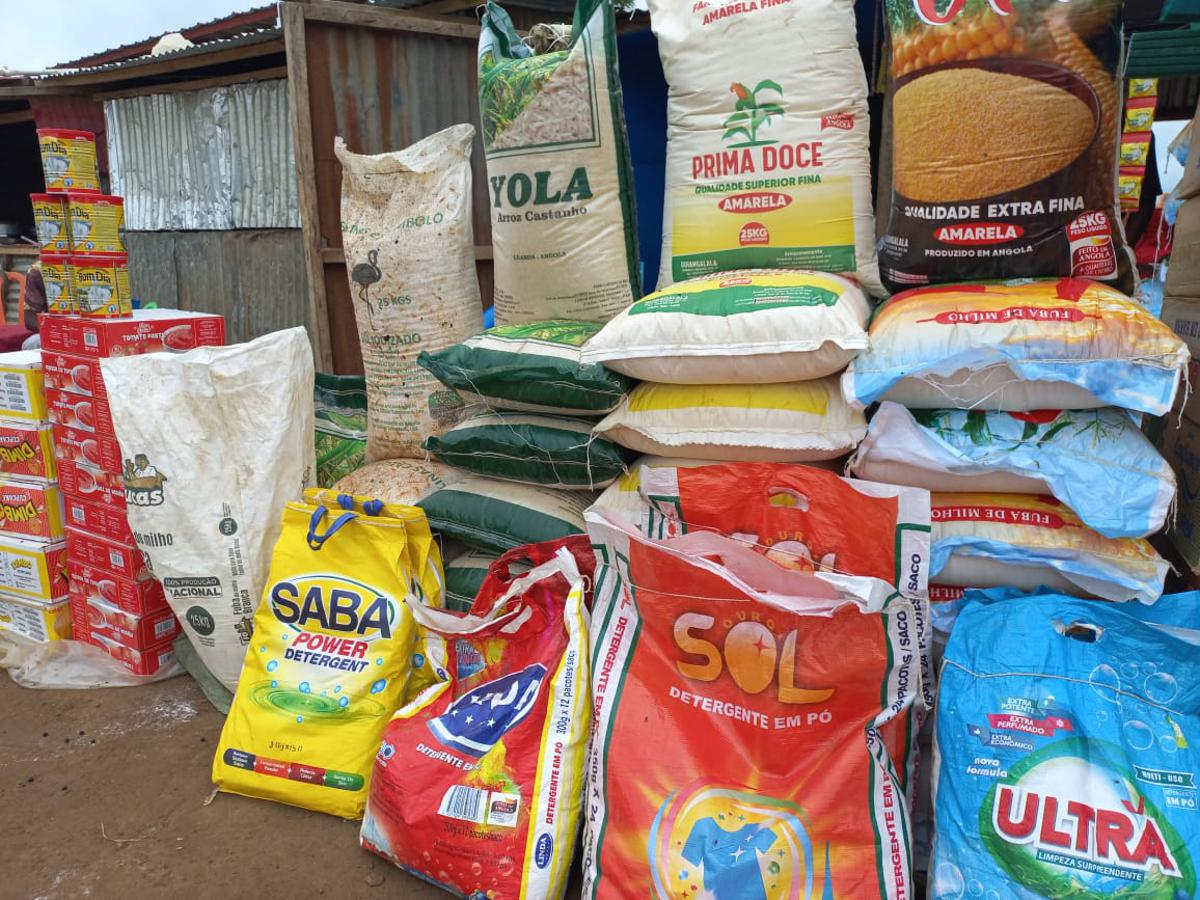
In the Democratic Republic of Congo, National Deputy Ron Bimwala proposed a reduction of Value Added Tax (TVA) to 1% on bottled water, basic foodstuffs, and hygiene products during the review of the 2027 Finance Bill on Friday, October 30, at the National Assembly.
This legislative proposal carries significant implications for the DRC's economy, particularly for consumers and businesses operating in the essential goods sector. If adopted, a drastic reduction in TVA from the standard 16% to 1% on these critical items would directly alleviate the financial burden on households grappling with the rising cost of living, potentially stimulating consumer spending in these categories. For businesses, while it might reduce the final price to consumers, it could also impact their input tax recovery mechanisms and overall cash flow, necessitating a careful review of their financial and operational strategies. The move signals a potential shift in fiscal policy towards greater social welfare, which could influence future legislative debates on taxation.
The legal context for this proposal is rooted in the DRC's fiscal framework, primarily Law No. 10/001 of 20 August 2010, which established the Value Added Tax (TVA) system, replacing the previous sales tax. This law, along with its various implementing decrees and ordinances, sets the standard TVA rate at 16% and outlines specific exemptions or zero-rated goods. The proposal is being considered within the annual legislative process of reviewing and adopting the Finance Bill (Loi de Finances), which is the primary instrument for setting the state's budget and fiscal measures for the upcoming year. The National Assembly, as the legislative body, holds the power to amend and approve such bills, making it the central arena for this debate.
The key parties involved in this development include National Deputy Ron Bimwala, who initiated the proposal, and the broader National Assembly, which is currently examining the 2027 Finance Bill. The Ministry of Finance, responsible for drafting the initial Finance Bill and managing the country's fiscal policy, is also a crucial stakeholder. Ultimately, the Congolese government, through its executive and legislative branches, will determine the fate of this proposal. Businesses involved in the production, import, and distribution of bottled water, basic foodstuffs, and hygiene products, as well as the general consumer population, are the primary beneficiaries or affected parties.
Practising attorneys advising clients in the consumer goods, retail, and manufacturing sectors in the DRC should closely monitor the legislative progress of the 2027 Finance Bill, specifically any amendments pertaining to TVA rates on essential products. Understanding the potential for reduced consumer prices, altered profit margins, and changes to tax compliance obligations will be critical for strategic business planning, pricing strategies, and supply chain adjustments. Legal professionals should be prepared to guide clients through the implications of any enacted changes to the TVA law, including potential adjustments to their accounting systems, invoicing practices, and tax declarations. The outcome of this specific proposal is not yet reported, but its consideration underscores a dynamic fiscal environment that requires vigilant legal oversight.