
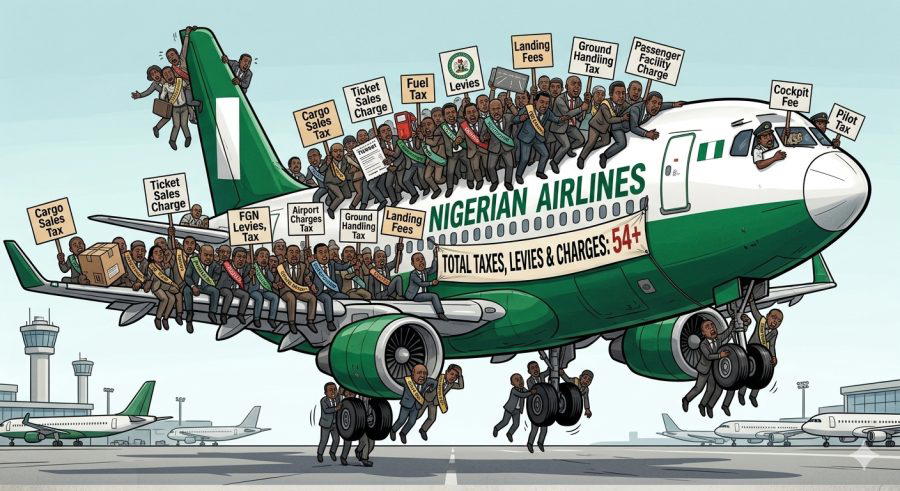
NCAA: Nigeria Airline Taxes Are 4, Not 54, Clarifying Operator Claims
Summary
- Nigerian airline operators claim they are subjected to 54 different taxes and levies.
- The Nigerian Civil Aviation Authority (NCAA) disputes this, stating airlines only pay four statutory taxes.
- Operators emphasize that civil aviation is an inherently expensive and capital-intensive business.
- This discrepancy highlights a significant point of contention regarding the financial burden on airlines in Nigeria.
The Disputed Tax Landscape
The inherent characteristics of civil aviation as a highly expensive and capital-intensive business mean that every financial imposition, regardless of its label, significantly impacts Nigerian airline operating costs.
Nigerian airline operators have recently brought to light a significant point of contention regarding the financial obligations imposed upon them, asserting that they are currently subjected to an astonishing 54 different taxes and levies. This claim underscores a perceived heavy Airline Operators of Nigeria tax burden, which they argue impacts their operational viability within the nation's airspace. The operators' collective voice highlights a deep-seated concern over the sheer volume of financial demands placed on their businesses.
This assertion, however, stands in stark contrast to the official position articulated by the Nigerian Civil Aviation Authority (NCAA). The regulatory body has publicly challenged the operators' figure, stating unequivocally that the actual number of statutory charges is dramatically lower. According to the NCAA, airlines are only required to pay four distinct taxes, creating a substantial discrepancy in understanding the true scope of Nigeria airline taxes 54 NCAA 4. This fundamental disagreement points to either a misunderstanding of regulatory frameworks or a broader issue concerning the definition and categorization of financial obligations within the Nigeria aviation sector levies.
Regulatory Framework and Compliance
The Nigerian Civil Aviation Authority (NCAA), as the primary regulatory body overseeing the nation's air transport sector, maintains a clear stance on the number of official levies applicable to airline operations. Their position is that only four specific taxes are mandated, a figure that directly contradicts the much higher number cited by the industry's operators. This official clarification from the NCAA aims to provide clarity on Aviation tax compliance Nigeria and the actual financial responsibilities of airlines.
This regulatory perspective suggests that any additional charges perceived by operators as "taxes" might fall outside the NCAA's direct purview or could be miscategorized. The authority's insistence on the lower figure implies a structured and limited set of financial requirements under its direct administration, aiming to ensure a predictable environment for Nigerian airline operating costs related to statutory payments. The disparity in figures thus raises questions about the comprehensive understanding of all financial outflows by both regulators and operators.
The Operators' Financial Realities
From the perspective of the Airline Operators of Nigeria, the enumeration of 54 distinct taxes and charges represents a significant and multifaceted financial strain. Their lament is rooted in the practical experience of managing numerous payments, whether officially designated as "taxes" by the NCAA or as other forms of levies, fees, or charges by various entities. This perceived extensive list contributes directly to the overall Nigerian airline operating costs, making the business environment particularly challenging.
The operators emphasize that the aviation industry, by its very nature, is a highly capital-intensive and expensive undertaking. Running an airline involves substantial investments in aircraft, maintenance, fuel, personnel, and infrastructure, all of which contribute to a complex financial model. The cumulative effect of what they perceive as 54 different financial obligations, regardless of their official classification, exacerbates these inherent costs and adds to the Airline Operators of Nigeria tax burden, impacting profitability and sustainability in the competitive market.
Implications for the Aviation Sector
The ongoing disagreement between airline operators and the Nigerian Civil Aviation Authority regarding the actual number of taxes highlights a critical issue within the nation's aviation sector. Whether the true figure is 4 or 54, the perception of an excessive Nigeria aviation sector levies burden can deter investment and hinder growth. This divergence in understanding about Nigeria airline taxes 54 NCAA 4 requires resolution to foster a more transparent and predictable operating environment for airlines.
The inherent characteristics of civil aviation as a highly expensive and capital-intensive business mean that every financial imposition, regardless of its label, significantly impacts Nigerian airline operating costs. A clear and unified understanding of all financial obligations is crucial for effective business planning and for ensuring the long-term viability of domestic carriers. Addressing this discrepancy is vital for promoting stability and confidence within the industry, ultimately benefiting both operators and the traveling public.
Source
How does this affect you?
Get an AI analysis of this article grounded in your jurisdictions, practice areas, and any policy documents you've uploaded to Wansom.
Finish Reading the Full Story and the Expert Analysis.
Get the latest legal & regulatory intelligence in Nigeria
Wansom is AI and can make mistakes.