
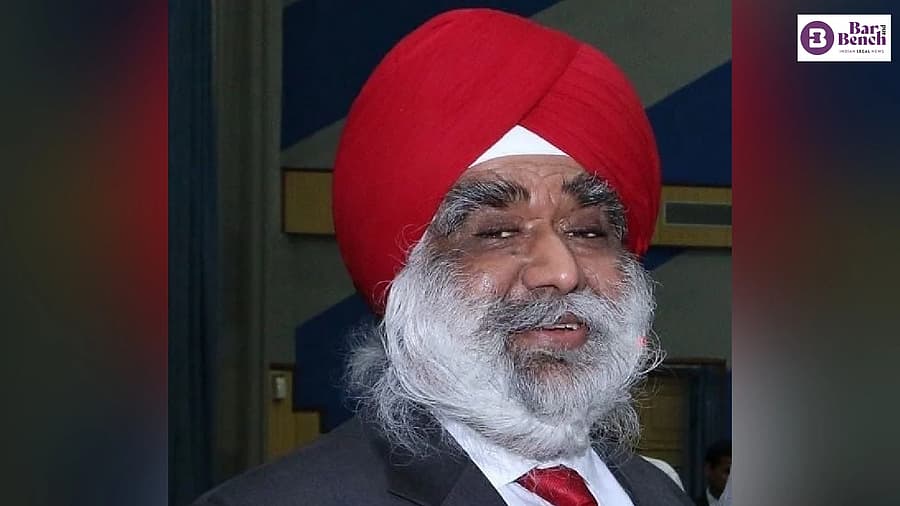
ITAT Delhi: Maninder Singh Wins Residential Property Tax Case on Law Office ALV
Summary
- The Income Tax Appellate Tribunal (ITAT) at Delhi ruled in favor of Senior Advocate Maninder Singh in a tax dispute concerning residential properties used as law chambers.
- The ITAT set aside a revision order by the Principal Commissioner of Income Tax (PCIT) that had questioned an assessing officer's (AO) assessment for the 2022-2023 assessment year.
- The Tribunal held that the PCIT had exceeded his revisional jurisdiction under Section 263 of the Income Tax Act, 1961 (now Section 377 of the Income Tax Act, 2025).
- The PCIT had objected to the AO's decision not to charge annual letting value (ALV) for three residential properties used as law offices.
- The ITAT confirmed that residential properties used for professional purposes, in accordance with the Delhi Master Plan 2041 (which superseded the Delhi Master Plan 2021), are not subject to ALV.
Tribunal Upholds Professional Use of Residential Property
Consequently, the Tribunal affirmed that no annual letting value could be appropriately computed during the assessment process, a conclusion the AO had correctly reached.
The Income Tax Appellate Tribunal (ITAT) in Delhi recently delivered a significant verdict favoring Senior Advocate Maninder Singh, a former Additional Solicitor General, in a tax dispute concerning the classification of residential properties utilized for his legal practice. The case, formally known as "Maninder Singh v. Circle 61", centered on an income tax assessment for the 2022-2023 assessment year. Specifically, the dispute arose after the Principal Commissioner of Income Tax (PCIT) issued a revision order challenging an earlier assessment made by an assessing officer (AO).
A two-member bench, comprising Vice President Mahavir Singh and Accountant Member Krinwant Sahay, ultimately set aside the PCIT's revisional order. The Tribunal concluded that the PCIT had overstepped the boundaries of his authority, specifically his revisional jurisdiction as defined under Section 263 of the Income Tax Act, 1961 (now Section 377 of the Income Tax Act, 2025). The core of the PCIT's objection was the AO's decision not to impose an annual letting value (ALV) on three residential properties that Mr. Singh had declared as being used exclusively for his law chambers.
Clarifying Revisional Powers and Property Valuation
The PCIT's contention was rooted in the premise that these residential properties, though used for professional purposes, should still be subject to an annual letting value calculation. Annual letting value, by definition, represents the hypothetical yearly rent a property could reasonably generate if it were leased out, particularly when a residential property is not occupied by its owner as a personal residence. The PCIT argued that the AO's omission to levy ALV rendered the assessment erroneous and prejudicial to the revenue, impacting the `Maninder Singh ITAT residential property tax` assessment.
However, the Income Tax Appellate Tribunal Delhi firmly rejected the PCIT's reasoning that residential premises could not legitimately serve professional functions. The Tribunal pointed to Clause 15.8 of the Delhi Master Plan 2021 (now superseded by the Delhi Master Plan 2041), which explicitly permits specified professions to conduct their activities from residential properties, confirming that such use is entirely within legal bounds. The ITAT emphasized that the assessing officer had diligently conducted all necessary verifications and inquiries regarding this specific issue. Consequently, the Tribunal affirmed that no annual letting value could be appropriately computed during the assessment process, a conclusion the AO had correctly reached. This ruling provides crucial clarity on the application of `Section 263 Income Tax Act revisional jurisdiction` in such scenarios, particularly concerning an `annual letting value law office`.
Implications for Professionals and Tax Assessments
This decision carries substantial weight for professionals, particularly lawyers, who operate their practices from residential premises in compliance with local regulations like the Delhi Master Plan 2041 professional use provisions (which superseded the Delhi Master Plan 2021). The ITAT's ruling reinforces the principle that when residential properties are legally converted and used for professional activities, they should not be automatically subjected to annual letting value for income tax purposes, provided the use aligns with municipal planning. This offers a protective precedent against arbitrary tax demands based on hypothetical rental income for such properties.
Furthermore, the judgment serves as a critical reminder of the limitations on the revisional powers of the Principal Commissioner of Income Tax. By explicitly stating that the PCIT exceeded his `revisional jurisdiction under Section 263 of the Income Tax Act`, the Tribunal has underscored the importance of AOs conducting thorough inquiries and verifications. If an AO has properly examined an issue and arrived at a reasoned conclusion, the PCIT cannot simply substitute their own view without demonstrating that the AO's assessment was genuinely erroneous and prejudicial to the revenue, thereby safeguarding the finality of well-considered assessments.
Practical Implications
This ruling clarifies the scope of revisional jurisdiction under Section 263 of the Income Tax Act and affirms that residential properties used as law chambers, in compliance with local master plans like Delhi's, are not subject to Annual Letting Value (ALV) for income tax purposes. Lawyers and compliance officers should note this precedent when advising professionals on tax implications for using residential premises as offices and in challenging PCIT orders that exceed their revisional powers.
Source
How does this affect you?
Get an AI analysis of this article grounded in your jurisdictions, practice areas, and any policy documents you've uploaded to Wansom.
Finish Reading the Full Story and the Expert Analysis.
Get the latest legal & regulatory intelligence in India
Wansom is AI and can make mistakes.