
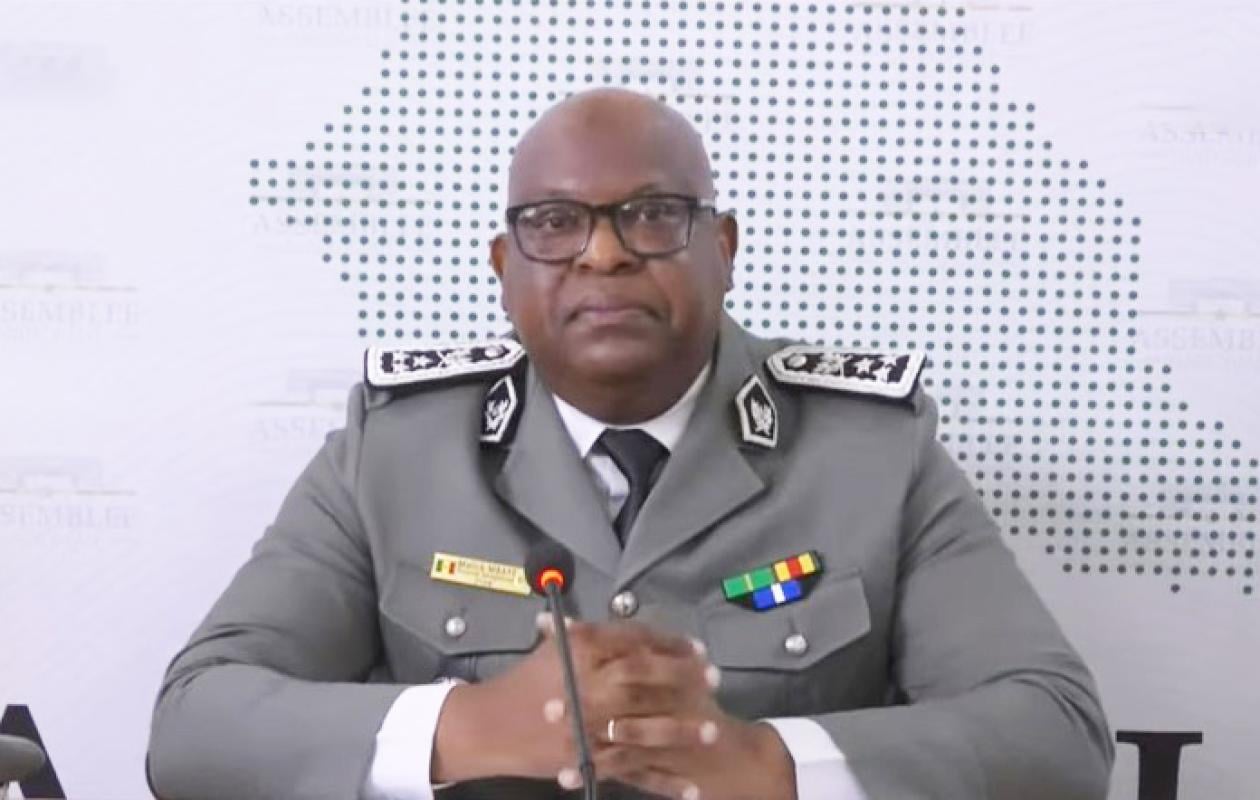
Malick Mbaye, Senegal: Clarifies Customs Exemptions Distinction
Summary
- Malick Mbaye, Director General of Customs, clarified the distinction between customs exemptions and suspensive regimes before a parliamentary commission.
- Suspensive regimes temporarily suspend duties for goods like those in warehouses or for transformation, with duties becoming payable if consumed domestically.
- Customs exemptions are permanent waivers, strictly requiring authorization by specific legal texts such as the Customs Code or Investment Code.
- The parliamentary commission is investigating the system of exemptions and the traceability of decisions, having also heard Jean Koné, Director General of Taxes and Domains.
- An exhaustive database of exemptions from 2014-2026 will be provided to deputies, and a register of exemptions since 2014 is under consideration to improve traceability.
Understanding Senegal's Customs Exemptions and Suspensive Regimes
The distinction articulated by Malick Mbaye is central to understanding Senegal's customs operations.
During a recent appearance before the parliamentary inquiry commission on tax exemptions, Malick Mbaye, the Director General of Customs for Senegal, drew a critical distinction between customs exemptions and what are known as suspensive regimes. He emphasized that these two mechanisms operate under fundamentally different regulatory frameworks. This clarification comes as the commission intensifies its examination of the broader system of exemptions and the crucial aspect of decision traceability within the Senegalese fiscal landscape.
The commission's ongoing investigation into these matters has also involved other key figures. On October 13, 2026, Jean Koné, the Director General of Taxes and Domains, provided testimony to the parliamentary body, addressing questions related to these issues and potential irregularities that might have occurred. The focus remains on ensuring clarity and accountability in the application of fiscal and customs policies across the nation.
Differentiating Fiscal Mechanisms in Senegal
The distinction articulated by Malick Mbaye is central to understanding Senegal's customs operations. Suspensive regimes, or régimes suspensifs douaniers Sénégal, are applied to specific categories of goods, such as those held in a customs warehouse, temporarily imported, or designated for transformation processes. Under these arrangements, the payment of duties and taxes is temporarily suspended, rather than permanently waived. The financial obligation for these duties and taxes only becomes exigible if the goods are subsequently released for consumption within the domestic market. Conversely, this obligation is extinguished entirely if the stipulated export requirements are fulfilled, ensuring the goods do not enter the local economy without appropriate taxation.
In contrast, actual customs exemptions, or exonérations fiscales Sénégal, represent a permanent waiver of duties and taxes. These exemptions are not granted at the discretion of the customs administration but must be explicitly mandated by specific legal texts. Key legislative instruments that provide for such Code des douanes Sénégal exonérations include the Customs Code, the Investment Code, the Mining Code, and the Petroleum Code. The Direction Générale des Douanes Sénégal, as clarified by its Director General, operates strictly within these legal parameters, verifying declarations, applying existing provisions, and liquidating duties, with the Public Treasury responsible for their recovery.
Enhanced Scrutiny and Traceability Initiatives
The parliamentary commission's work underscores a significant push for greater oversight and traçabilité exonérations fiscales Sénégal. A core objective of the inquiry is to establish a comprehensive understanding of how exemption decisions are made and tracked. To bolster this effort, Malick Mbaye has committed to providing deputies with an exhaustive database detailing all exemptions recorded between 2014 and 2026. Furthermore, the commission is actively exploring the creation of a dedicated register for exemptions granted since 2014, aiming to enhance transparency and accountability in fiscal and customs matters.
Operational controls are already in place to support these objectives. The GRET system, which is integrated into the GAIN platform, plays a vital role in monitoring quotas and ensuring the traceability of economic regimes. Beyond the initial customs clearance process, rigorous post-clearance verifications are conducted by specialized investigative services and a joint Tax-Customs brigade. The commission's hearings are ongoing, with Colonel Malang Diedhiou also having provided testimony, though no definitive conclusions have been announced at this stage of the proceedings.
Practical Implications
Lawyers and compliance officers in Senegal should note the increased parliamentary scrutiny on customs and tax exemptions. They must advise clients to meticulously review and document all claims for exemptions, ensuring strict adherence to specific legal texts, given the emphasis on traceability and the distinction between suspensive regimes and legal exemptions, to mitigate future compliance risks.
Source
Source: Original reporting via Seneweb.
How does this affect you?
Get an AI analysis of this article grounded in your jurisdictions, practice areas, and any policy documents you've uploaded to Wansom.
Finish Reading the Full Story and the Expert Analysis.
Get the latest legal & regulatory intelligence in Senegal
Wansom is AI and can make mistakes.