
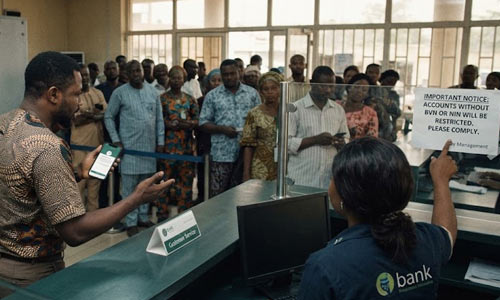
Supreme Court: Nigerian Bank Account Restriction Violates Customer Rights
Summary
- The relationship between a bank and its customer in Nigeria is fundamentally contractual.
- Banks are obligated to honor valid customer mandates, like cheques, when sufficient funds are available.
- The Nigerian Supreme Court has long held that a bank's failure to do so constitutes a breach of contract.
- This legal precedent protects customer rights against arbitrary account restrictions.
The Contractual Core of Banking
The Supreme Court bank customer rulings serve as a critical safeguard, ensuring that financial institutions cannot arbitrarily refuse to process transactions or unilaterally restrict access to funds without robust legal justification.
In Nigeria, the fundamental relationship between a bank and its clientele is primarily contractual. This foundational agreement dictates the responsibilities and entitlements of both parties, forming the bedrock of the bank customer relationship Nigeria. When an individual or entity deposits funds into an account, they are entering into a legally binding contract where the bank assumes the critical role of safeguarding these financial assets and committing to execute the customer's legitimate instructions.
This arrangement is built on mutual trust and clear obligations. Customers entrust their financial resources to the bank, expecting secure management and prompt execution of their directives. In return, the bank undertakes to honor valid bank mandates customer funds, such as processing withdrawals or payments, provided that the account holds sufficient balances. This reciprocal duty is not merely an operational guideline but a core legal commitment, defining the parameters within which financial institutions must operate concerning their customers' assets.
Supreme Court's Definitive Stance on Bank Obligations
A pivotal aspect concerning Nigerian bank account restriction customer rights is the enduring legal precedent established by the Supreme Court. This highest judicial authority in Nigeria has consistently affirmed that a bank's failure to honor a customer's valid mandate, specifically citing the example of a cheque, when adequate funds are demonstrably present in the account, unequivocally constitutes a breach of contract bank Nigeria. This authoritative judicial interpretation underscores the gravity with which the legal system views a bank's adherence to its contractual duties.
The Supreme Court bank customer rulings serve as a critical safeguard, ensuring that financial institutions cannot arbitrarily refuse to process transactions or unilaterally restrict access to funds without robust legal justification. This precedent holds significant weight in contemporary discussions surrounding customer account freezing Nigeria, as it sets a stringent standard for banks, requiring them to demonstrate legitimate and legally sound reasons for any actions that impede a customer's access to their own money. It reinforces the principle that a bank's power over customer funds is not absolute but is circumscribed by its contractual obligations and established legal norms.
Protecting Customer Rights Against Restrictions
The contractual nature of the bank-customer relationship, rigorously reinforced by the Supreme Court's pronouncements, provides a robust legal framework for protecting customer rights against unwarranted account restrictions. When a bank fails to uphold its end of this agreement by refusing to honor a valid instruction, such as a cheque, despite the availability of sufficient funds, it exposes itself to significant legal liability for breach of contract. This principle is absolutely crucial for understanding the potential legal recourse available to individuals or businesses whose accounts may be subject to arbitrary or unjustified restrictions.
Therefore, any instance where a bank declines to process a customer's cheque or other legitimate mandate, without a valid and legally defensible reason and in the presence of adequate funds, directly contravenes these well-established legal principles. This situation highlights the imperative for financial institutions to meticulously review and align their internal policies on account restrictions with existing legal precedents. Simultaneously, it underscores the importance for customers to be fully aware of their rights and the legal avenues available to them in circumstances where their access to funds is improperly impeded.
Practical Implications
Lawyers should advise clients on their rights and potential legal recourse when banks restrict accounts, referencing established Supreme Court precedents on bank-customer contractual obligations. Compliance officers in financial institutions must review internal policies on account restrictions to ensure adherence to customer rights and mitigate risks of breach of contract claims.
Source
How does this affect you?
Get an AI analysis of this article grounded in your jurisdictions, practice areas, and any policy documents you've uploaded to Wansom.
Wansom is AI and can make mistakes.