
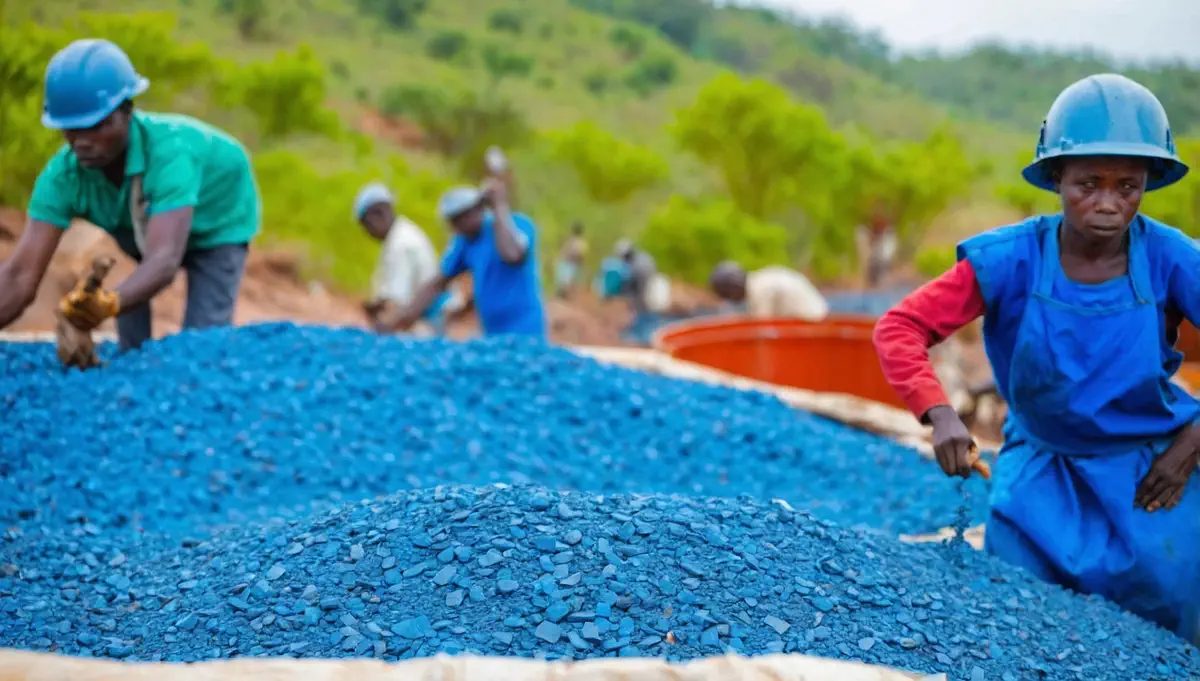
Congo Rewrites Its Mining Rulebook: A Concentrate Export Ban, a New By-Product Tax and a Mining Code Overhaul in Waiting
Summary
Concentrate ban: an order signed on 29 June 2026 by the Mines, Foreign Trade and Economy ministers bans copper and cobalt concentrate exports immediately, with discretionary one-year "strategic" waivers, and repeals the 2023 exemptions.
Limited bite: Congo exported 696,725 tonnes of cathode against 53,926 tonnes of concentrate in Q1 2026. Ivanhoe says a similar ban has been enforced for close to ten years, and Kamoa-Kakula's concentrate is now smelted in Congo.
By-product tax: trace and ultra-trace minerals recovered during refining are valued with a 55% coefficient and charged royalties alongside the main mineral, after a three-month transition ending in late September or early November depending on the start date.
Strategic minerals: since May 2026, lithium and five other minerals pay a 10% royalty, alongside cobalt, germanium and coltan.
Code overhaul: a bill by Serge Chembo N'Konde would amend 40+ articles of the 2018 code, adding production limits, state stockpiles, specialised oversight agencies, fines up to US$1 million and prison terms up to 20 years. The Chamber of Mines held an emergency forum on 15–17 July.
Trade law: the ban sits uneasily with GATT Article XI, and its five-week publication delay raises transparency issues under Article X. The tax and code bill test stability clauses and investment protections.
Instrument 1: The Concentrate Export Ban
The order: An interministerial order dated 29 June 2026, signed by Mines Minister Louis Kabamba Watum, Foreign Trade Minister Julien Paluku Kahongya and Deputy Prime Minister for the Economy Daniel Mukoko Samba, states that "the export of copper and cobalt concentrates is prohibited". It took effect immediately, but became public only on 6 August 2026, when Reuters reported its contents.
What it does:
Element | Effect |
|---|---|
Ban | Exports of copper and cobalt concentrates prohibited with immediate effect |
Waivers | The Mines Minister may grant one-year waivers in undefined "strategic" circumstances |
Previous regime | Repeals the 2023 export framework and the exemptions granted under it |
By-products | Introduces a new tax regime for economically significant mining by-products, with a three-month transition |
Why it changes less than the headline suggests. Congo already exports most of its copper as refined metal:
Congo copper exports, Q1 2026 | Tonnes |
|---|---|
Refined copper cathode | 696,725 |
Copper concentrate | 53,926 |
Concentrate bans are not new either. Congo introduced them in 2013, 2019 and 2023, and each was softened by waivers when local smelting capacity fell short. Ivanhoe Mines said a ban on unbeneficiated concentrate exports has been in place and enforced for close to ten years, with multiple derogations issued to Kamoa-Kakula since production began in 2021. Its concentrate is now smelted on site or at the Lualaba Copper Smelter in Kolwezi. Ivanhoe's Kipushi mine holds a separate derogation for zinc concentrate.
Where it still bites. The asset most exposed is Kamoa-Kakula, owned by Ivanhoe, Zijin Mining and the Congolese state, which StoneX estimates produced about 389,000 tonnes of copper concentrate in 2025, around 64% of Congo's concentrate output. The real change is in the waiver system: exemptions under the old regime are gone, and new ones depend on the Mines Minister's discretion, for one year at a time.
Cobalt hydroxide is not concentrate. Congo's main cobalt export, hydroxide, is a processed intermediate and is governed separately by ARECOMS export quotas. The concentrate ban adds a control on the form of exports, while quotas control the volume of cobalt leaving the country.
Instrument 2: The By-Product Tax, the Bigger Change
What it taxes. The same 29 June order creates a tax regime for economically significant mining by-products. It applies to trace and ultra-trace minerals recovered during refining: metals present in small quantities in copper and cobalt ore that are captured as secondary products when the main metal is refined.
How it works.
Element | Rule |
|---|---|
Scope | Trace and ultra-trace minerals recovered during refining, across a wide range of minerals |
Valuation | A 55% valuation coefficient applied to calculate the taxable and royalty base |
Royalties | Charged alongside the royalty on the main mineral, not instead of it |
Transition | A three-month transition period before the regime applies in full |
Why it matters more than the ban. Refinery streams in the Copperbelt contain minor and strategic metals that operators have often treated as secondary credits. Placing them formally in the royalty base, at a set valuation, gives the state a direct, separately calculated claim on that value. It also makes metallurgical accounting a compliance issue: operators will need to track, assay and report minor-metal recoveries much more precisely.
The link to strategic minerals. In May 2026, Congo added lithium, tantalum, niobium, tungsten, uranium and rare earths to its list of strategic minerals, alongside cobalt, germanium and coltan. Strategic minerals pay a 10% royalty, compared with 3.5% for ordinary non-ferrous metals such as copper. Where a by-product is itself a strategic mineral, such as germanium, the combined effect of the higher royalty rate and the new valuation rule could be significant.
When it starts. The order provides a three-month transition, but the published reporting does not say whether it runs from signature on 29 June or from publication or notification in August. Counted from signature, it ended around 29 September 2026. Counted from early August, it ends in early November 2026. Operators should be preparing now for either date, and watching for implementing guidance from the Mines Ministry and tax authorities.
Instrument 3: The Mining Code Overhaul Bill
The bill. A private member's bill by lawmaker Serge Chembo N'Konde, entered into review on 13 June 2026 and sent to the government for comment, would amend more than 40 articles of the 2018 Mining Code. The bill argues that parts of the 2018 code have become outdated and that greater state oversight is needed. Its author told Semafor that stronger oversight was needed to track mineral exports and account for the revenue they generate.
What it proposes:
Area | Proposal |
|---|---|
Strategic and reserved minerals | Expanded state control, including broader powers to limit production |
Stockpiles | Legal basis for the state to create strategic mineral stockpiles |
Oversight | Stronger regulatory and anti-fraud supervision through specialised mining agencies |
Local content and communities | New provisions on local content and community development |
Enforcement | Fines of up to US$1 million and prison terms of up to 20 years |
The industry response. The Chamber of Mines called an emergency forum for 15 to 17 July 2026 in Kinshasa to build a common industry position and assess whether another code revision was warranted. It warned that the speed of the process risked insufficient consultation and could fuel regulatory uncertainty and institutional tensions. Miners argue that the sector's problems lie less in the 2018 code than in its implementation: overlapping mandates, unauthorised interventions and conflicting interpretations. Benjamin Katabuka, who heads US explorer KoBold Metals in Congo, said established rules should not be changed "in the middle of the game".
Where it stands. Since July, there has been no public sign that the bill has advanced to a parliamentary vote. For now it is a pending proposal, but one that would give a legislative basis to policies the government is already pursuing administratively, such as ARECOMS's cobalt buy-back powers and strategic quota.
The Bigger Picture: A Layered System of State Control
The three instruments are part of a wider tightening across Congo's mining sector in 2026. Each targets a different point in the value chain:
Control point | Instrument | Regulator or authority | What it controls |
|---|---|---|---|
How much cobalt leaves | Cobalt export quotas (96,600 tonnes a year for 2026–2027) | ARECOMS | Export volume |
In what form minerals leave | Concentrate export ban (29 June order) | Mines Minister (waivers) | Export form, pushing processing onshore |
How much the state collects | Strategic-mineral royalties (10%) and the by-product tax (55% coefficient) | Mines Ministry and tax authorities | Fiscal take |
Who supplies the mines | Subcontracting law and the 2027 local-content regime | ARSP | Local content |
Who owns the mines | 10% Congolese participation, including 5% for employees | Mines Ministry | Ownership |
Who the state partners with | US–Congo strategic minerals partnership and DRC-USA Task Force | Cabinet | Strategic alignment |
The legal foundation | 2018 Mining Code and the pending overhaul bill | Parliament | The framework itself |
The common thread. Congo is moving from a model in which the state mainly collected royalties and taxes, to one in which it actively manages supply, processing location, suppliers, ownership and buyers. Some of these levers are administrative orders that can change quickly. The code bill would anchor more of them in statute.
The risk. Each instrument on its own may be defensible. Together, and changed frequently, they raise the overall regulatory burden and the uncertainty that the Chamber of Mines warned about. Investors weigh the predictability of a regime as heavily as its level of taxation or control.
The Trade and Investment Law Analysis
1. The concentrate ban and WTO rules
An export ban is a quantitative restriction that GATT Article XI generally prohibits. Congo's possible defences are narrow:
Article XX(g), conservation of exhaustible natural resources, requires the measure to be made effective together with restrictions on domestic production or consumption.
Article XX(i) allows export restrictions on domestic materials needed by a domestic processing industry, but only while their domestic price is held below world prices under a stabilisation plan, and not to protect that industry.
WTO panels have rejected similar measures: China's export restrictions on raw materials and rare earths, and, more recently, a panel ruling against Indonesia's nickel ore export ban, which Indonesia appealed into the non-functioning Appellate Body. A beneficiation ban like Congo's would face similar arguments if challenged, though practical enforcement is limited.
2. Transparency and legal certainty
The 29 June order became public only on 6 August, more than five weeks after it took effect. GATT Article X requires laws and regulations affecting exports to be published promptly so that traders and governments can become acquainted with them. Retroactive application of an unpublished order, especially to shipments in transit, would be vulnerable to challenge both domestically and in trade law. The discretionary waiver system adds a second transparency issue: without published criteria or waiver lists, operators cannot predict who will receive exemptions.
3. Fiscal stability and the by-product tax
The 2018 Mining Code reduced the period of fiscal and customs stability for existing title holders. A new royalty base for by-products, and the higher royalty rate for newly designated strategic minerals, may be tested against the stability protections in individual mining conventions and the transitional provisions of the 2018 Code. Operators with earlier conventions that include broader stabilisation should review them carefully.
4. The code overhaul and investor protection
Congo is a party to the ICSID Convention and to bilateral investment treaties with several countries. Large changes to the mining code, such as powers to limit production, create stockpiles or impose criminal sanctions, can engage fair and equitable treatment standards if applied to existing investments in ways that frustrate legitimate expectations or lack due process. The Chamber of Mines' complaint about the speed and limited consultation of the reform is, in legal terms, a due-process argument.
5. A pattern across Africa
Congo is not alone. Zimbabwe taxes raw lithium and chrome exports, Ghana's new cocoa law reserves half the crop for local processing, and Zambia has used temporary suspensions of its 10% copper concentrate export duty to manage smelter bottlenecks. Across the continent, governments are using export controls and fiscal tools to push value addition at home.
What It Means for Each Stakeholder
Copper and cobalt producers with concentrate
Most exposed: Kamoa-Kakula and any operator still shipping concentrate under old exemptions. What to do: apply early for a one-year strategic waiver if domestic smelting capacity is insufficient, with evidence of smelter availability, offtake commitments and processing plans. Prepare for annual renewal and for waiver decisions resting with the Mines Minister alone. Accelerate on-site or domestic smelting where feasible.
Refiners and integrated producers
Most exposed to the by-product tax: any operation recovering minor metals during refining. What to do: map every minor metal recovered at each plant, set up assay and metallurgical accounting systems that can withstand audit, model the cost of royalties under the 55% coefficient, and plan for the transition period ending either around late September or early November 2026.
Smelter operators and processing investors
The ban reinforces the policy of processing in Congo. Smelters with spare capacity could gain feed and negotiating leverage. Investors in new processing capacity have a stronger policy case, but must price in power supply, reagents and logistics.
Traders and offtakers
Concentrate offtake contracts with Congolese mines need force majeure and change-in-law provisions that address export bans and waiver refusals. Buyers should expect more cathode and processed intermediates and less concentrate from Congo.
Investors and lenders
The combination of export controls, new fiscal rules, local-content enforcement, equity requirements and a pending code overhaul raises regulatory risk. Lenders should test project models against waiver refusal, higher royalties and possible production limits under the bill. Stabilisation clauses and treaty protections deserve fresh legal review.
Explorers and new entrants
The code bill is the main uncertainty for projects not yet in production. New entrants, including US-backed explorers under the bilateral partnership, have publicly warned against changing rules mid-game. Watch whether the bill advances, and engage through the Chamber of Mines.
The Congolese state
The by-product tax could raise meaningful revenue if it can be measured and collected, and the ban supports domestic processing. But frequent, poorly publicised changes, such as an order disclosed five weeks after it took effect, undermine the investment Congo needs to build that processing capacity.
Lawyers and advisers
The work includes waiver applications, royalty and by-product tax computations, stability-clause reviews, offtake contract amendments, and submissions on the mining code bill.
Key Dates
Date | Event |
|---|---|
May 2026 | Lithium, tantalum, niobium, tungsten, uranium and rare earths added to the strategic minerals list (10% royalty) |
13 June 2026 | Mining code amendment bill entered into review |
29 June 2026 | Interministerial order bans copper and cobalt concentrate exports and creates the by-product tax |
15–17 July 2026 | Chamber of Mines emergency forum on the code bill |
6 August 2026 | Order made public via Reuters |
Late September or early November 2026 | End of the three-month by-product tax transition, depending on the start date |
What to Watch
What to Watch
Milestone | Why it matters |
|---|---|
Published waiver lists | Who gets one-year exemptions from the concentrate ban, and on what criteria |
First collections of the by-product tax | How the 55% coefficient is applied in practice and which minerals are captured |
Implementing guidance | The exact start date and computation rules for the by-product tax |
The code bill | Whether it reaches Parliament, and in what form |
Smelter capacity | Whether domestic processing can absorb concentrate without waivers |
Frequently Asked Questions
Has Congo banned copper and cobalt concentrate exports? Yes. An order signed on 29 June 2026 and made public on 6 August prohibits concentrate exports with immediate effect, with one-year waivers possible in strategic circumstances.
Does the ban affect most of Congo's copper exports? No. In the first quarter of 2026, Congo exported 696,725 tonnes of refined copper cathode and 53,926 tonnes of concentrate. The ban mainly affects operations that still export concentrate, notably Kamoa-Kakula.
What is the by-product tax? A new tax regime on trace and ultra-trace minerals recovered during refining, using a 55% valuation coefficient, with royalties charged alongside those on the main mineral. It has a three-month transition period.
What does the mining code bill propose? A private member's bill by Serge Chembo N'Konde would amend more than 40 articles of the 2018 Mining Code: expanding state control over strategic minerals, allowing state stockpiles, strengthening oversight agencies, and introducing fines of up to US$1 million and prison terms of up to 20 years.
Is the code bill law? No. It was sent to the government for comment in June and has not been passed by Parliament.
Citations
- 1.• Congo bans copper and cobalt concentrates exports, official order says, Reuters via Kitco (6 August 2026)
- 2.• Congo rewrites copper and cobalt export rules anew, The Deep Dive
- 3.• DRC Bans Copper and Cobalt Exports: What Do We Need to Know?, StoneX
- 4.• Congo bans copper and cobalt concentrate exports as global supply risks grow, The Oregon Group
- 5.• Congo Bans Copper and Cobalt Concentrates Exports, Official Order Says, Kamoa Capital (citing Ivanhoe's clarification)
- 6.• DRC copper-cobalt export ban: winners, losers and the $14,000 copper supply shock, Skillings
- 7.• Congo's planned mining law reform could dent investor confidence, industry warns, Reuters via Mining Weekly (14 July 2026)
- 8.• DR Congo's mining law reform is raising tensions with investors, Semafor (20 July 2026)
- 9.• Congo adds lithium to strategic minerals in higher tax bracket, Mining.com
Finish Reading the Full Story and Expert Analysis.
Get the latest legal & regulatory intelligence in DR Congo
Wansom is AI and can make mistakes.