
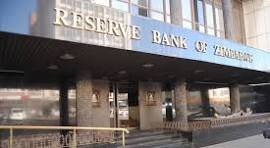
WHAT THE RESERVE BANK OF ZIMBABWE PATNERSHIP WITH INDIA MEANS FOR DIGITAL TRANSACTIONS COST FUTURE
Introduction
The Reserve Bank of Zimbabwe (RBZ) is in negotiations with NPCI International Payments Limited (NIPL) on payments technology. This negotiation seeks to propose a system would connect banks, mobile-money operators and fintech companies through shared infrastructure while lowering transfer costs and faster digital transactions. The proposed arrangement follows India's earlier partnership to develop an instant-payment system in Namibia.
Analysis
While Zimbabwe already has an existing Domestic infrastructure , the RBZ operates the national real time gross settlement system for high value transfers, and a national switch handles retail interbank card and electronic transactions. Mobile money operators run large closed loop ecosystems that dominate everyday retail payments, and interoperability between those ecosystems and bank accounts has been a recurring policy theme.
The Zimbabwe Gold (ZiG) currency, introduced in 2024, operates alongside widespread use of foreign currency, which adds a currency dimension to any new payments platform.
LEGAL ANALYSIS
From a legal and regulatory standpoint , a shared national platform will almost certainly require licensing under the National Payment Systems Act, and the RBZ will need to decide whether NIPL is a technology supplier to a Zimbabwean operator or the operator itself. The distinction drives everything else. A supplier model keeps the licensed operator, and therefore the RBZ's enforcement reach, inside Zimbabwe. An operator model places a foreign entity within the supervisory perimeter and raises questions about jurisdiction, dispute resolution and the enforceability of regulatory directions.
There is a need for clear participation rules . Especially if the RBZ makes connection mandatory for banks and licensed providers, it will need a clear legal basis in the Act or in directives, and affected institutions will want transition periods and fee schedules published in advance. If participation is voluntary, adoption will depend on pricing and on whether the existing national switch continues to offer a competitive alternative.
Incorporating Contract terms will carry much of the practical regulatory weight. Intellectual property in the platform, step in rights, escrow of source code, service levels, audit access for the RBZ and exit arrangements are the provisions that determine whether the central bank retains real control after go-live. Public procurement and state-contract rules may also apply if the RBZ is acting as a procuring entity, and counsel should confirm which regime governs.
BUSINESS AND OPERATIONAL ANALYSIS
For banks and larger payment providers, the decision to connect is a board matter. It affects core systems, third-party risk, product strategy and capital spending. Boards should expect management to present a documented assessment of the platform's resilience, the provider's financial standing and the institution's dependence on a single infrastructure.
The RBZ has its own governance exposure. A national platform chosen through a government-to-provider negotiation invites scrutiny on transparency, value for money and conflicts of interest. Publishing the evaluation criteria and the main terms would reduce the risk of later challenge and would help market participants plan.
For banks, the commercial effect depends on fee structure. Lower interchange and switching fees will compress revenue from transaction services, and institutions that rely on those fees will need to replace them with volume or value-added services. For fintech and smaller payment providers, a common rail with open participation lowers the cost of reaching customers and could reduce their dependence on bank partners.
Mobile money operators face a sharper strategic question. Interoperability with bank accounts benefits customers but weakens the lock-in that closed ecosystems enjoy. Operators with large user bases may support the platform in principle and resist the pricing that makes interconnection cheap for competitors.
Merchants and corporate users stand to gain from faster settlement and, potentially, from lower collection costs. Diaspora remittance flows are a further commercial interest, although the report does not say whether cross-border functionality with India or other markets is within the scope of the talks.
The central opportunity is interoperability on common standards, which can lower unit costs and widen access for customers outside the formal banking sector. Regulatory clarity may improve if the RBZ uses the project to consolidate scattered directives into one participation framework. Fintechs and licensed providers that integrate early could build products on the new rails before competitors do. Banks with strong compliance and data controls could use the project to rationalise legacy systems. A link to India's payments network, if included, could reduce the cost of remittances and trade settlement, although this depends on terms not yet disclosed.
Conclusion
Zimbabwe's talks with NIPL concern who builds, operates and controls the rails on which retail payments will run. The promised gains are lower costs and faster transfers. The terms that determine whether those gains are secured, and whether regulatory control is retained, are not yet public. The regulatory trajectory points towards a shared national platform on foreign technology, which raises licensing, data governance and liability questions that existing law only partly answers.
Decision-makers should remember three practical points. The 31 October date is a negotiation target and not a compliance deadline. The contract will matter more than the headline announcement. Institutions that prepare their data, compliance and contractual positions now will be better placed when terms emerge.
Citations
- 1.National Payment Systems Act [Chapter 24:23] (Zimbabwe).
- 2.Reserve Bank of Zimbabwe Act [Chapter 22:15].
- 3.Banking Act [Chapter 24:20].
- 4.Cyber and Data Protection Act [Chapter 12:07].
- 5.Money Laundering and Proceeds of Crime Act [Chapter 9:24].
- 6.Exchange Control Act [Chapter 22:05] and related exchange control directives.
- 7.Reserve Bank of Zimbabwe directives and guidance applicable to payment service providers and mobile-money operators (current versions to be confirmed).
- 8.Financial Action Task Force, International Standards on Combating Money Laundering and the Financing of Terrorism and Proliferation (the FATF Recommendations).
- 9.Agreement between India's NPCI International Payments Limited and the Namibian authorities on an instant-payment system (text to be obtained for comparison).
- 10.Ayodeji Adegboyega, "Zimbabwe turns to India's payments giant to cut transfer costs and speed up digital transactions," Business Insider Africa, 5 October 2026.
Finish Reading the Full Story and the Expert Analysis.
Get the latest legal & regulatory intelligence in Zimbabwe
Wansom is AI and can make mistakes.