
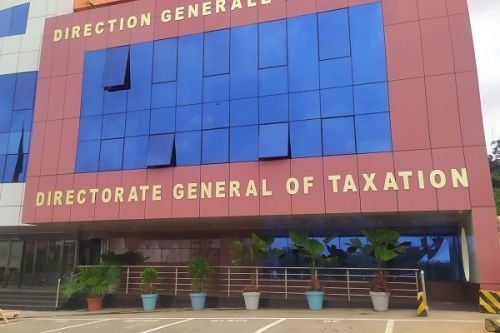
Cameroon: Tax Administration Tightens Digital Payroll Integration and IRPP Enforcement
Cameroon’s Directorate General of Taxation (Direction Générale des Impôts – DGI) has escalated its enforcement of electronic withholding tax compliance on employment income, implementing strict audit criteria for personal income tax (Impôt sur le Revenu des Personnes Physiques – IRPP) across corporate payrolls.
Operationalized under recent Finance Law directives and automated through the DGI’s central digital filing architecture, the campaign targets two high-risk exposure areas: the strict withholding and monthly remittance of progressive IRPP brackets reaching an effective marginal rate of 38.5% (inclusive of the municipal surcharge), and the systematic recalculation of undervalued employee perks and benefits-in-kind.
For multinational enterprises, oil and gas operators, financial institutions, and corporate employers in Cameroon, the third-quarter 2026 audit cycles signal heightened regulatory scrutiny of executive compensation packages and cross-border pay structures.
Progressive IRPP Withholding & CAC Surtax Enforcement
Under the General Tax Code (Code Général des Impôts – CGI) and administrative circulars governing salary deductions, employers act as collection agents under strict statutory liability to withhold and remit IRPP by the 15th of each month.
The DGI’s automated audit protocols verify compliance against the standard progressive schedule on net taxable employment income:
Progressive Scale: Taxable brackets range from 10% on initial tiers up to 35% on taxable income tiers.
Municipal Surcharge (CAC): Employers must systematically add the mandatory 10% Additional Council Tax (Centimes Additionnels Communaux – CAC) calculated on the baseline IRPP liability.
Effective Top Marginal Rate: For high-earning personnel with gross taxable earnings exceeding XAF 5,000,000 per month (or annual equivalents exceeding statutory ceilings), the application of the 35% nominal top bracket plus the 10% CAC surcharge drives the effective top statutory marginal rate to 38.5%.
Effective Rate Calculation:
Base IRPP Bracket = 35.0%
Additional Council Tax (10% of Base IRPP) = 3.5%
Total Effective Marginal Rate = 38.5%
The DGI's digital matching mechanisms cross-reference company-declared IRPP withholdings against social security reporting filed with the National Social Insurance Fund (Caisse Nationale de Prévoyance Sociale – CNPS), flagging discrepancies immediately for desktop review.
Standardized Valuation of Benefits-in-Kind & Allowances
Corporate tax audits historically identified severe under-reporting in executive fringe benefits. In response, the DGI's latest audit guidelines enforce statutory caps and mandatory percentage valuations calculated against gross taxable remuneration:
Housing (Logement): Standardized statutory valuation assessed at 15% of the employee's total gross cash remuneration. Discretionary, off-payroll corporate housing leases or direct landlord payments that circumvent this valuation benchmark are treated as disguised compensation subject to retroactive withholding.
Company Vehicles (Véhicules): Standardized valuation at 10% of gross remuneration per allocated vehicle. The DGI has instructed field inspectors to scrutinize shared pool-car designations that conceal executive-assigned transport.
Utilities & Domestic Services: Mandatory statutory additions are enforced, including 4% for electricity, 2% for water, and 5% per domestic servant funded directly or indirectly by the corporate entity.
Compliance Framework: Payroll Withholding vs. Audit Realities
Compensation Component | Statutory Assessment Rule | Common Audit Exposure | Immediate Corrective Measure |
Executive Base Pay | Progressive brackets (10%–35%) plus 10% CAC surtax. | Miscalculation of CAC multiplier; incorrect application of professional expense caps. | Reconfigure ERP/payroll tax tables to compute the effective 38.5% ceiling correctly. |
Housing Support | Statutory rate fixed at 15% of gross cash pay. | Treating employer-leased housing as an exempt operational expense rather than a benefit-in-kind. | Integrate rental allowances and direct lease values into the monthly IRPP tax base. |
Company Cars | Statutory rate fixed at 10% of gross cash pay per vehicle. | Labeling permanent executive vehicles as general "field fleet" to bypass the benefit tax. | Audit vehicle allocation logs and apply the 10% rate to designated personnel. |
Overtime / Premia | Fully taxable alongside base employment earnings. | Disguising overtime as non-taxable expense reimbursements (frais de mission). | Reconcile time-tracking logs with payroll slips to prevent retroactive reclassification. |
Strategic Actions for Corporate Counsel and CFOs
To preempt unilateral tax assessments, penalty surcharges (which can reach up to 100% in cases of bad-faith omissions), and payroll re-evaluations during Q3 2026 audit reviews, organizations should implement the following steps:
Re-baseline Benefits-in-Kind Accounting: Conduct a comprehensive inventory of all expatriate and executive benefit packages. Ensure housing contracts, utilities, and corporate vehicle provisions strictly apply the 15%, 10%, and utility percentage formulas within monthly payroll software.
Execute Inter-Agency Reconciliation Audits: Perform a mock reconciliation between monthly DGI e-filings, annual tax summaries, and CNPS social security returns. Significant variances between gross bases reported to CNPS and taxable bases reported to DGI represent the primary trigger for field inspections.
Formalize Expatriate Secondment Agreements: Review split-payroll and shadow-payroll arrangements for international assignees to confirm that in-country allowances and home-country top-ups are correctly declared within Cameroon’s territorial tax perimeter.
Prepare Documented Defense Files: Centralize housing leases, fleet logs, and proof of electronic tax payments within the DGI portal to ensure immediate response capability when receiving standard verification requests (demandes d'éclaircissements).
Finish Reading the Full Story and the Expert Analysis.
Get the latest legal & regulatory intelligence in Cameroon
Wansom is AI and can make mistakes.